The legal cash deposit limit in Nigeria without triggering mandatory regulatory reporting is ₦10,000,000 for individuals and ₦50,000,000 for corporate accounts. Depositing cash amounts above these thresholds requires banks to automatically file a Cash Transaction Report (CTR) with the Nigerian Financial Intelligence Unit (NFIU). Intentionally breaking a large sum into smaller payments to stay under these limits is an illegal practice called “deposit structuring” or “smurfing,” which will get your bank account blacklisted and flagged for money laundering investigations.
The ₦10 Million Limit: How to Deposit Large Cash in Nigeria Without Flagging Your Bank Account
In today’s highly regulated financial environment, banks are expected to operate with maximum transparency, accountability, and strict adherence to anti-money laundering (AML) regulations. Compliance is not optional, it is the backbone of trust, stability, and long-term survival. Yet, beneath everyday deposit activities lies a subtle but dangerous threat that often goes unnoticed: “deposit structuring in banking”.
Many banking professionals focus on customer-driven risks, which includes fraudulent deposits, suspicious withdrawals, or large cash movements. However, a more complex and often overlooked issue is staff-driven deposit structuring, where internal actions, whether intentional or careless, can expose financial institutions to severe regulatory consequences.
This article explores what deposit structuring in banking means, why it is a compliance risk, how banks detect it, and the critical role staff behavior plays in either preventing or enabling this dangerous practice.
What Is Deposit Structuring in Banking?
Deposit structuring refers to the deliberate or repeated splitting of large cash deposits into smaller amounts, often to avoid triggering regulatory reporting thresholds. In many jurisdictions, including Nigeria and across global banking systems, large cash transactions must be reported to regulatory authorities for monitoring.
When deposits are intentionally broken into smaller amounts that fall below reporting limits or thresholds, it raises a serious red flag. This behavior is commonly associated with attempts to bypass regulatory scrutiny, making it a major concern in anti-money laundering (AML) compliance.
However, not all structuring is customer-driven. In some cases, bank staff may knowingly or unknowingly assist in structuring deposits, creating serious internal compliance failures. In most cases, customers funds and account are being investigated when they receive a huge inflow. To understand how this works read my complete guide on Why Is My Bank Account Under Investigation? (Banker Explains What You Need to Know)
A Quiet Conversation with Loud Consequences (An Example/Scenario Of How Deposit Structuring Works In Banking)
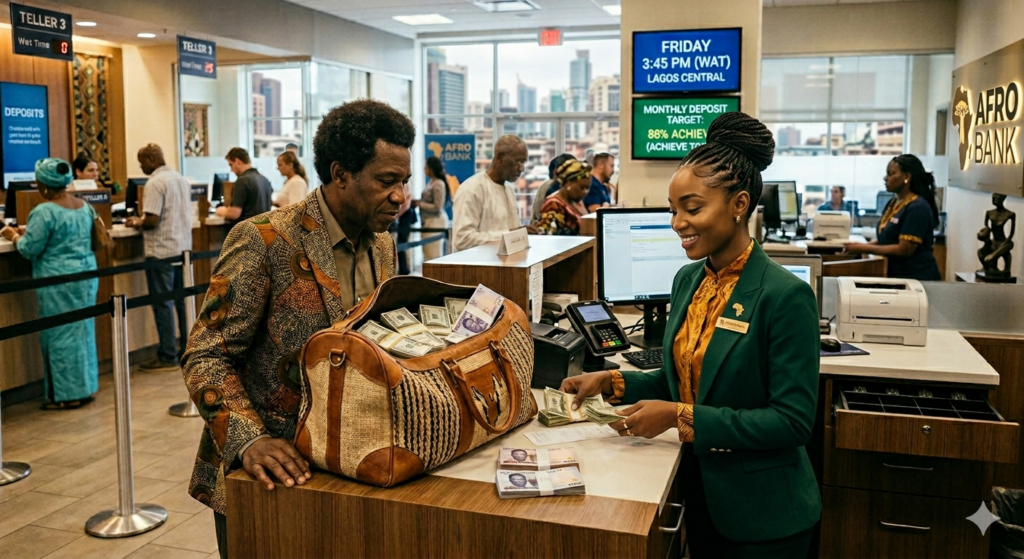
Imagine a busy Friday afternoon at a retail bank branch, a well known customer steps up to the counter with a bag containing 19,000,000 in cash to deposit into his account. When the teller mentions that a cash transaction report must be filed for amounts over 10,000,000 the customer frowns, grumbling about the extra paperwork and the delay. Eager to help/keep the VIP customer happy and also anxious to secure the deposit toward the branch’s monthly volume target, the teller smiles reassuringly and whispers to the customer, “Let me tell you what, Let’s deposit 10,000,000 today, and you can bring the remaining 9,000,000 back on Monday. That way, we keep it simple.”
It feels like excellent customer service, a win-win situation, but in reality, it is a ticking regulatory time bomb.
Why Deposit Structuring Is a Major Compliance Risk
Deposit structuring is not just a technical violation, it directly threatens the integrity of the financial system. Here’s some of the major compliance risks associated with deposit structuring.
1. Undermines Regulatory Reporting
Banks are required to report suspicious or large transactions to regulators. When structuring occurs, it disrupts this reporting mechanism, creating gaps in financial monitoring. This weakens the bank’s ability to detect illegal financial flows such as money laundering or fraud.
2. Triggers Regulatory Penalties
Failure to detect or prevent structured deposits can lead to heavy fines, sanctions, and reputational damage. Regulators expect banks to maintain strong transaction monitoring systems, and any lapse, especially linked to internal staff, can result in severe consequences.
3. Erodes Customer Trust
Trust is fundamental in banking. Once customers perceive that a bank is involved in questionable practices, whether intentionally or due to negligence, it damages the institution’s reputation. A single compliance scandal can lead to long-term loss of customer confidence.
The Core Rule: What is the Cash Deposit Limit in Nigeria?
[Single Cash Deposit] ───> ₦10,000,000+ (Individual) ───> Mandatory CTR Filed to NFIU
                                                                     │
[Single Cash Deposit] ───> ₦50,000,000+ (Corporate) ────> Mandatory CTR Filed to NFIU
How Banks Detect Deposit Structuring
Modern financial institutions rely on a combination of systems and human oversight to identify structured transactions. Some of the ways include:
1. Transaction Monitoring Systems
Banks use automated monitoring tools that analyze customer behavior patterns. These systems flag repeated deposits just below reporting thresholds, multiple deposits across different branches or accounts and unusual transaction timing or frequency. These patterns help compliance teams identify potential structuring risks early.
2. Behavioral Analysis
Detection goes beyond numbers. Banks also assess the behavior of customers and staff. They access the sudden changes in deposit patterns, inconsistent explanations for transaction activity and frequent visits to different branches. These indicators often suggest an attempt to manipulate deposit reporting processes.
3. Internal Controls and Audits
Regular audits and internal reviews play a key role. These checks ensures that staff follow proper reporting procedures, suspicious transactions are escalated promptly and compliance gaps are identified and corrected. Strong internal controls reduce the risk of staff-assisted deposit structuring.
The Trap of “Deposit Structuring” (Smurfing)
5 Specific Red Flags Banks Watch Out For
-
- The “Under-the-Threshold” Pattern: Repeated cash deposits that consistently sit right below the reporting line (e.g., depositing ₦9.8 million or ₦9.9 million multiple times in a short window).
- Multiple Branch Hopping: Depositing varying amounts of cash into the same account across different physical branches within a few hours.
- Sudden Activity Spikes: An account that typically processes ₦200,000 a month suddenly receiving a single cash influx of ₦8 million without any prior profile updates.
- Rapid Cash Transit: Massive cash deposits followed immediately by rapid outbound internet transfers or international wire requests, leaving the account balance at zero within minutes.
- Unexplained Third-Party Structuring: Having multiple unrelated individuals (agents or “smurfs”) deposit varying sub-threshold cash amounts into your single account from different locations simultaneously.
How to Legitimately Prove Your Source of Funds
-
- For Real Estate Sales: A certified copy of the executed Deed of Assignment, the land survey plan, and a formal receipt of payment signed by both parties.
- For General Business/Trader Sales: Valid, serialized point-of-sale invoices, customs clearing documents (for importers), or a clean corporate audited financial statement detailing cash flow metrics.
- For Gratuities, Inheritances, or Wills: A legal letter of administration from a probate court or a certified bank check issued by an executing law firm.
- For Agriculture/Commodity Trading: Waybills, community market storage receipts, or supply contracts with structured agribusiness aggregators.
Step-by-Step: How to Deposit Large Cash Safely
Step 1: Update Your Know-Your-Customer (KYC) Tier
Step 2: Inform Your Relationship Manager in Advance
Step 3: Complete the Large Cash Declaration Form Transparently
The Hidden Role of Staff in Deposit Structuring
One of the most critical and under-discussed risks in banking is internal staff involvement in structured deposits. Please be reminded that the Bank AML/CFT policy is of critical importance, and strict compliance is required. It is important to note that:
-
All inflows, especially cash, must be deposited directly by the customer or their authorized representatives.
-
For any cash deposit above the CBN threshold, a valid ID card and detailed address of the depositor must be obtained.
-
Under no circumstances should staff act as depositors into customer accounts, to avoid associated risks.
1. Unintentional Staff Involvement
In many cases, front-line staff such as tellers may not fully understand the implications of structuring. They may accept repeated small deposits without questioning patterns,
process transactions without escalating unusual activity and fail to recognize compliance red flags. This lack of awareness can unknowingly enable structuring.
2. Deliberate Manipulation
More concerning is the possibility of intentional staff involvement. This may include advising customers on how to avoid reporting thresholds, accepting deposits in ways that bypass monitoring systems and splitting transactions across accounts or time periods.
Such actions represent serious internal fraud and compliance breaches, exposing the bank to regulatory penalties.
2. Pressure and Weak Controls
Sometimes, staff behavior is influenced by pressure to meet deposit targets, weak oversight from management and lack of strict compliance enforcement. These conditions create an environment where structuring risks can thrive unnoticed.
Real-World Example of Deposit Structuring Risk
Consider a situation where a customer deposits large sums of cash regularly, but instead of making one transaction, chooses to make multiple deposits over several days. If bank staff continue to process these deposits without questioning the pattern or escalating it, the bank unknowingly becomes part of a structured transaction scheme. Over time, such behavior can:
- Trigger regulatory investigations
- Lead to compliance violations
- Damage the bank’s reputation
This highlights the importance of vigilance at every level of banking operations.
Warning Signs of Structured Deposits in Banks
Recognizing early indicators is key to preventing compliance breaches. Some common warning signs include:
- Repeated deposits just below reporting thresholds
- Customers making multiple deposits in a short timeframe
- Deposits spread across different branches or accounts
- Unusual urgency from customers during transactions
- Staff processing transactions without adequate documentation
When these signs appear, they must be investigated promptly.
How Deposit Structuring Affects Banking Compliance
Deposit structuring directly impacts a bank’s compliance framework in several ways. They include:
Weakens AML Systems – Structured deposits make it difficult for banks to detect illegal financial flows, weakening anti-money laundering efforts.
Increases Operational Risk – When staff fail to follow proper procedures, it creates operational vulnerabilities that can escalate into larger compliance failures.
Attracts Regulatory Scrutiny – Banks with repeated structuring cases often come under stricter regulatory supervision, increasing audit frequency and compliance pressure.
Preventing Deposit Structuring in Banking
To effectively manage the risk of deposit structuring in banking, banks must adopt a proactive approach. These approaches are discussed below.
1. Strengthening Staff Training
Staff must be educated on what deposit structuring means, why it is illegal or risky and how to identify suspicious patterns. A well-trained employee is the first line of defense against compliance breaches.
2. Enhancing Transaction Monitoring
Banks should continuously improve their monitoring systems to detect evolving structuring patterns, especially in high-risk sectors such as cash-intensive businesses.
3. Enforcing Strict Internal Controls
Clear procedures must be in place to ensure that all suspicious transactions are reported, staff responsibilities are clearly defined and compliance breaches are addressed immediately. Strong internal controls reduce the chances of staff-driven manipulation.
4. Promoting a Compliance Culture
Beyond systems and policies, banks must build a culture where compliance is prioritized over short-term gains. Staff should feel empowered to report suspicious activities without fear of retaliation.
The Nigerian and African Context
In many African banking environments, cash transactions remain dominant. This creates a higher risk of structured deposits, especially in informal business sectors. Banks operating in Nigeria and across Africa must be particularly vigilant about:
- Cash-heavy transactions
- Weak documentation practices
- Limited financial literacy among customers
By addressing these challenges, institutions can strengthen their compliance frameworks and protect their reputations.
Frequently Asked Questions (FAQs)
What is the maximum cash amount I can deposit in a Nigerian bank without being questioned?
Will my bank account be frozen automatically if I deposit over ₦10 Million at once?
Is it illegal to split my cash deposits across multiple bank branches to avoid paperwork?
Can a third party deposit a large amount of cash into my account on my behalf?
How long does it take for a bank to unfreeze an account flagged for large cash deposits?
What is deposit structuring in banking?
Deposit structuring is the act of splitting large deposits into smaller amounts to avoid triggering regulatory reporting requirements.
Is deposit structuring illegal?
Yes, when done intentionally to evade reporting, it is considered a serious compliance violation and may be linked to financial crimes.
How do banks detect deposit structuring?
Banks use transaction monitoring systems, behavioral analysis, and internal audits to identify suspicious deposit patterns.
Can bank staff be involved in structuring?
Yes, staff can be involved either intentionally or unintentionally, making internal controls and training essential.
What are the risks of structured deposits in banking?
They include regulatory penalties, reputational damage, weakened AML systems, and loss of customer trust.
Conclusion: Transparency Protects Your Wealth
Deposit structuring in banking is more than just a technical irregularity. It is a hidden risk that threatens compliance, operational integrity, and customer trust. While much attention is given to customer behavior, the role of bank staff in enabling or preventing structuring cannot be overstated. From front-line tellers to compliance officers, every individual plays a critical role in safeguarding the institution.
For banks like where I work and especially for professionals working at the operational level, understanding and addressing this risk is essential. By strengthening monitoring systems, improving staff awareness, and enforcing strict compliance standards, financial institutions can protect themselves from regulatory penalties and maintain the trust of their customers.