The primary difference between a POD (Payable on Death) account and a Will is that a POD account bypasses probate court completely, whereas a Will must go through probate before any assets are distributed. Furthermore, a POD designation contractually overrides a Will. If your Will states that all your assets go to one person, but your bank’s POD form lists someone else, the bank is legally obligated to hand the cash directly to the named POD beneficiary upon your death.
In Africa, especially Nigeria’s banking system and family homes, one silent issue continues to cause confusion, hardship, and unnecessary disputes which is “what happens to money in a bank account when the owner dies”? Many people assume that once a person passes away, their next of kin can simply walk into the bank and collect the funds. In reality, things are rarely that simple. This is where Payment on Death (POD) becomes a powerful, yet still underutilized financial planning tool.
This guide equips bank customers with clear knowledge of Payment on Death (POD) and provides bank staff with a structured explanation for customer education, compliance, and advisory purposes.
Payment on Death or Payable on Death(POD) Account vs. Will: The Ultimate Estate Planning Guide
When planning what happens to your financial assets after you pass away, two of the most common tools available are a Payable on Death (POD) account and a traditional Last Will and Testament. While both aim to distribute your wealth, they operate under completely different legal frameworks. Navigating these options can mean the difference between a seamless cash transfer to your family and a grueling, months-long nightmare in probate court.
Drawing from my extensive hands-on experience as a banking operations officer, this comprehensive guide breaks down how these tools function, compares them directly, exposes hidden traps, and shares real-world insights from the banking hall.
What Is Payment on Death or Payable on Death(POD)?
Payment on Death (POD) is a banking instruction that allows an account holder to name a beneficiary who will receive the funds in the account after the account holder’s death. While the account holder is alive, the beneficiary has no access to the money. The account remains fully under the control of the owner until death. Only then does the bank release the funds to the named beneficiary, after verification.
How Does a POD Account Work?
A Payable on Death (POD) account (also known in some regions as a “Totten Trust” or a formal beneficiary designation) is a contract between you and your bank. It allows you to designate one or more individuals as beneficiaries who will automatically inherit the money in your checking, savings, or certificate of deposit (CD) accounts when you pass away.
┌────────────────────────────────────────┐
│         ACCOUNT OWNER IS ALIVE         │
│ Beneficiary has ZERO access or rights  │
└───────────────────┬────────────────────┘
                    │
                    ▼ [Owner Passes Away]
┌────────────────────────────────────────┐
│      PROBATE COURT IS BYPASSED         │
│  Account completely avoids the Will    │
└───────────────────┬────────────────────┘
                    │
                    ▼ [At the Bank Counter]
┌────────────────────────────────────────┐
│      BENEFICIARY CLAIMS FUNDS          │
│ Needs: Death Cert + Government ID      │
└────────────────────────────────────────┘
Setting it up is incredibly simple and entirely free. You visit your branch, complete a single-page beneficiary designation form, and provide the bank with the full name, social security or national identity number, and contact information of your chosen beneficiary. The bank updates your account profile with a “POD flag,” and the setup is complete.
Transfer on Death (TOD) vs. Payable on Death (POD)
People frequently mix up these terms, but the operational distinction is simply about the asset type:
-
- POD (Payable on Death): Used strictly for liquid cash assets held at commercial banks (checking accounts, savings accounts, and fixed deposits).
- TOD (Transfer on Death): Used strictly for brokerage accounts, individual stocks, bonds, mutual funds, and in some jurisdictions, real estate or vehicle titles.
Which Accounts Are Eligible for POD in Nigerian Banks?
In Nigeria, POD arrangements are commonly applied to:
- Savings accounts
- Current accounts
- Fixed deposit accounts
Some banks describe this as a beneficiary mandate or special POD instruction but in Nigerian banking practice, POD may also be referred to as beneficiary mandate, POD Instruction or Special Account Nomination. Therefore, the key principles of Payment on Death (POD) are:
- The beneficiary has no access while the account holder is alive
- The account holder retains full control during their lifetime
- Funds are released only upon verified death documentation
Can a POD Beneficiary Withdraw Money While I am Alive?
As a bank staff member, this is the number one question concerned elderly customers ask me at my desk. The answer is an absolute, unconditional NO.
A POD beneficiary has exactly zero ownership rights, zero access, and zero visibility into your bank account while you are alive.
-
- They cannot check your balance.
- They cannot sign cheques or make ATM withdrawals.
- They cannot see your transaction history.
- You retain full, unrestricted rights to spend every single cent in the account, change the beneficiary, or close the account entirely at any moment without their permission.
Your beneficiary only gains rights the exact moment you pass away. Until then, they are merely a name on a secure server.
POD Account vs. Will: Direct Structural Breakdown
To make the best decision for your estate, you must understand how these two financial instruments stack up against each other under legal scrutiny.
| Feature |
Payable on Death (POD) Account |
Last Will & Testament |
| Legal Scope |
Covers only the specific bank account it is attached to. |
Covers your entire estate (property, cash, personal items). |
| Probate Court |
Bypasses probate completely. Cash transfers directly. |
Must go through probate before assets are distributed. |
| Speed of Access |
Days. Beneficiary gets cash almost immediately. |
Months to Years. Delayed by court approvals. |
| Privacy Level |
High. Kept strictly confidential between bank and beneficiary. |
Low. Becomes a matter of public record in court. |
| Cost |
100% Free to set up at any bank. |
Often requires paid legal or attorney assistance. |
The Golden Rule of Estate Banking: POD Overrides a Will
The most critical takeaway is that a POD designation completely supersedes a Will. If your Will explicitly states, “I leave all my money to my son, John,” but your bank account’s POD form designates your daughter, Sarah, the bank is legally obligated to give 100% of the cash to Sarah.
Banks are financial institutions bound by account contracts, not courts of equity. We do not read Wills at the teller counter. We follow the contractual beneficiary form on our screens.
The Pitfalls of Payable on Death Accounts (The Bank Staff Perspective)
While POD accounts are excellent tools for bypassing probate, they are not flawless. Over my years working inside bank operations, I have witnessed several grieving families hit massive roadblock because the account holder fell into these structural traps.
1. The Minor Child Disaster
Many parents list their minor children (under 18 or 21, depending on local laws) as POD beneficiaries. This is a massive operational mistake. Banks legally cannot hand thousands of dollars in cash directly to a minor. If the account holder passes away, the funds will be frozen, and the family will be forced to hire a lawyer and go to court anyway to establish a legal guardianship or conservatorship to manage the money.
2. Equal Distribution Inflexibility
If you name three children as equal POD beneficiaries, the bank will require a separate claim from each. If one child is unreachable, uncooperative, or living abroad, it can stall the payout process for the remaining siblings. Furthermore, POD accounts do not allow for complex instructions (e.g., “Give my son $10,000 only after he graduates college”). It is always an immediate, all-or-nothing cash split.
3. The Tragic Predeceased Beneficiary Loop
If your named POD beneficiary passes away before you do, and you forget to update the bank records to name a new one, the POD designation automatically becomes null and void. Upon your death, the bank account lapses back into your general estate, meaning the money will be frozen and dragged right into the probate court you tried so hard to avoid.
4. Shortchanging the Funeral & Estate Debt
Because POD funds bypass probate and go directly into the beneficiary’s hands, those funds are completely isolated from your executor. If all your cash is tied up in a POD account, your estate may have zero liquid money left to pay for your funeral costs, final medical expenses, or outstanding taxes. This forces your executor to liquidate physical property or ask the POD beneficiary to voluntarily give the money back to cover costs—a scenario that frequently triggers intense family feuds.
Insider Advice: How to Protect Your Family
If you want to use a POD account effectively based on how banks actually operate behind closed doors, follow this advice:
-
- Review Your Beneficiaries Annually: Treat your bank account like a living document. Every January, log into your mobile banking app or visit a branch to verify that your named beneficiaries are still correct, alive, and aligned with your current life situation.
- Coordinate with Your Executor: Ensure your executor or the person handling your funeral arrangements knows which accounts are POD and who has the funds, so they can coordinate immediate post-life expenses without financial stress.
- Use a Trust for Minor Children: If your heirs are minors, do not use a standard POD. Instead, consult an attorney to set up a Living Trust, and name that trust as the beneficiary on your bank account.
How Payment on Death Works (Step‑by‑Step)
Although procedures vary slightly from bank to bank or country by country, but in Africa especially Nigeria, the process generally follows this structure:
Step 1: Beneficiary Nomination/POD Registration
The account holder completes a POD or beneficiary nomination form at the bank, stating who should receive the funds upon death and providing:
- Full beneficiary name
- Relationship to account holder
- Identification details
Step 2: No Interference During Lifetime
If the account holder is still alive, the POD beneficiary cannot:
- Withdraw money from the account
- Give instructions on the account
- Monitor the account
Full control remains with the account holder as the account functions normal, beneficiary has no rights or access and account holder can modify or cancel POD at any time.
Step 3: Event of Death/Notification After Death
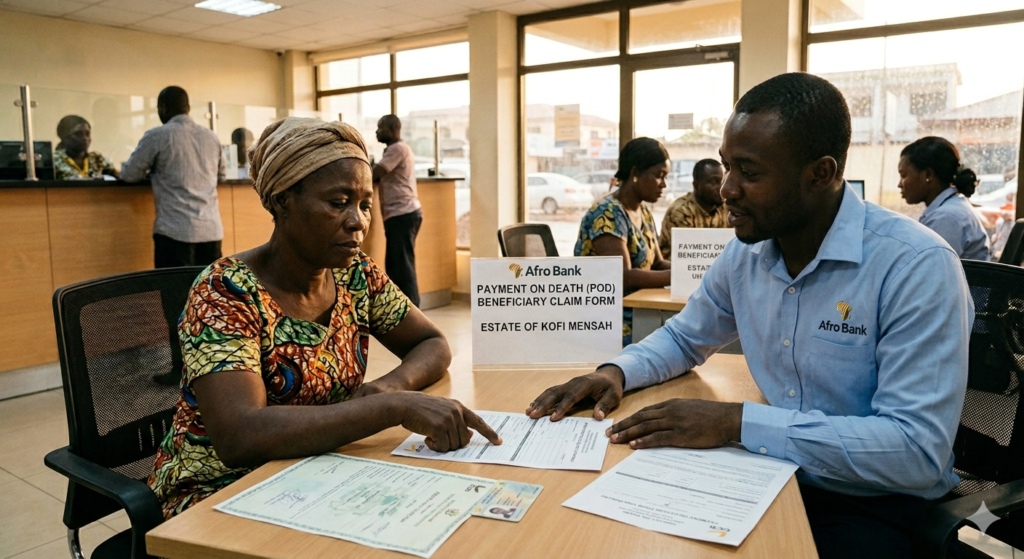
When the account holder passes away, the beneficiary or family notifies the bank and submits required documents, such as:
- Death certificate or sworn declaration
- Valid means of identification
- Any additional documents requested by the bank
Step 4: Verification & Fund Release
After due diligence and compliance checks or once the bank completes verification and compliance checks, funds are paid directly to the beneficiary, bypassing probate delays.
Why Payment on Death Is Important for Bank Customers
1. Faster Access to Funds
In Nigeria or Africa, probate and Letters of Administration can take months or even years. During that period, families often struggle to access basic funds for urgent needs. POD helps close this gap.
2. Immediate Support for Loved Ones
POD funds can be used quickly for:
- Funeral and burial expenses
- Emergency & Medical bills
- Rent, utility and household needs
- Children’s school fees
At a time of emotional stress, quick access to money provides real relief.
3. Reduced Legal Costs and Stress
Court processes are not only slow but also expensive. POD helps families avoid:
- Lawyer fees
- Court filings
- Repeated bank visits
4. Fewer Family Disputes
Clear documentation reduces arguments, accusations, and power struggles, especially in blended families or complex family structures.
POD vs Next of Kin: Key Clarification for Customers
This is one of the most misunderstood issues in Africa/Nigerian banking. Being named as next of kin does not automatically guarantee access to the money. Without a clear POD instruction, banks are legally required to insist on probate or Letters of Administration, regardless of who the next of kin is.
Therefore, this distinction must be clearly explained by bank staff, and below is a key difference between Next Of Kin and POD:
- Next of Kin: Mainly for contact, emergencies, and administrative purposes
- POD Beneficiary: The person legally entitled to the funds after death
Read More About Next of Kin Does NOT Automatically Inherit Money In The Bank: The Real Process Explained
Payment on Death and Wills: Which One Applies?
For bank accounts, POD instructions usually overrides a will. Banks are legally obligated to follow the latest valid POD mandate on record for a specific account.
This means if your will names Person A and your POD form names Person B, the bank will typically pay Person B. That is why smart financial planning requires consistency between:
- Your will
- Your bank mandates (POD)
- Your beneficiary instructions
That is why we, as bank staff encourage customers to ensure consistency between POD instructions and their wills.
Important Limitations To Keep In Mind About Payment on Death
1. Not a Full Estate Plan
Payment on Death is useful, but it is not a complete estate plan. It covers only the named account and does not apply to:
- Land and real estate
- Family land
- Business assets & interests
- Shares and investments outside the account (unless specified)
2. Minor Beneficiaries
Naming minors can be complicated. If a beneficiary is under 18, banks may require the following before releasing funds to minors:
- A legal guardian
- A trustee arrangement
- Additional legal documentation may apply
3. Customary and Religious Considerations
Nigeria’s inheritance framework includes customary and religious laws. While banks respect POD mandates, families should plan carefully to prevent disputes.
4. Outstanding Debts
In certain circumstances, debts or legal claims against the estate may still affect how assets are handled.
Who Should Seriously Consider Payment on Death/Who Should Be Encouraged to Set Up POD??
Many people do not know what POD is all about and how it works, but as bank staff, we recommend POD to these people below:
- Salary earners
- Bank customers with savings or fixed deposits
- Small business owners or SME owners
- High‑net‑worth individuals
- Retirees and pre‑retirees professionals
- Anyone who wants clarity, speed, and reduced family stress
Therefore, POD works best alongside a valid and updated will, accurate bank records (so keep your records clear & straight) and a professional financial or legal advice.
Staff Talking Points
During our interactions with our customers, we clearly let them know that:
- “POD does not give the beneficiary access to their account while they are still alive.”
- “Next of kin is not the same as a beneficiary of POD.”
- “Without POD, probate may be required.”
- “They can change POD details anytime.”
- “POD helps their family access funds faster and easier more than letters of administration or probate.” To know more about how Letter of administration works, read my quick guide 0n Probate or Letter of Administration
Frequently Asked Questions
1. What does it mean when a bank account is designated as “Payable on Death” (POD)?
A Payable on Death (POD) designation means that the account holder has contractually named one or more specific beneficiaries who will automatically inherit the cash assets in that bank account immediately upon the holder’s passing.
2. What is the fundamental difference between a POD account and a Will?
A POD account is a direct banking contract that covers only that specific bank account and bypasses probate court entirely. A Last Will and Testament covers an individual’s broader estate (cars, houses, personal items) but must pass through the lengthy probate process before any assets can legally be distributed to heirs.
3. Which takes legal priority if my Will and my POD account list different people?
The POD account designation always wins. Legally, a beneficiary contract on a bank account overrides conflicting instructions inside a Will. If your Will says all your cash goes to your son, but your bank’s POD form lists your daughter, the bank must distribute 100% of the funds to your daughter.
4. Can my named POD beneficiary check my balance or withdraw money while I am alive?
No. A POD beneficiary has zero access, zero ownership, and zero visibility into your banking information during your lifetime. They have a contingent interest that only activates upon your death; until then, you can spend the money or close the account entirely.
5. How does a beneficiary legally claim the money in a POD account after the owner dies?
To claim the funds, the beneficiary must visit a branch counter and provide the bank with a certified copy of the account holder’s death certificate along with their own government-issued identification card.
6. What types of financial accounts are eligible for a POD or beneficiary status?
You can add a beneficiary designation to almost all liquid personal banking products, including:
-
- Checking and Savings accounts
- Certificates of Deposit (CDs) and Money Market accounts
- Individual Retirement Accounts (IRAs) and 401(k) plans
- Investment and brokerage accounts (typically called “Transfer on Death” or TOD accounts)
7. Does it cost any money to set up a POD account at a bank?
No. Designating a POD beneficiary is a completely free service provided by financial institutions during your lifetime, unlike establishing a Living Trust, which often requires significant legal or attorney fees.
8. What is the primary operational advantage of using a POD designation?
The biggest benefit is speed of access. While funds caught up in a probate court battle can be frozen for several months or years, a POD beneficiary can typically access the liquid cash within a couple of weeks after obtaining a certified death certificate.
9. Can I name more than one beneficiary on a single bank account?
Yes, you can list multiple beneficiaries. However, you must carefully navigate local regulations, as state or regional banking laws often permit only an equal distribution of the funds among the surviving designees.
10. Can I name an alternate or secondary beneficiary on a POD form?
Generally, no. Standard bank account agreements do not allow you to list alternate or contingent beneficiaries (e.g., “Give this to Mary, but if she dies, give it to Robert”). If the beneficiary passes away before you, the designation automatically lapses.
11. What happens if my named POD beneficiary dies before I do?
If the beneficiary predeceases you and you do not officially update the bank records with a new name, the POD protection breaks. Upon your death, the account will lapse directly back into your probate estate, subjecting the cash to the exact legal delays you sought to prevent.
12. Are funds in a Payable on Death account completely safe from creditors?
No. If the original account holder dies with heavy unpaid debts, back taxes, or lines of credit, the estate’s executor or government agencies can legally assert claims against the funds in a POD account to settle those obligations.
13. Why is naming a minor child as a POD beneficiary considered a pitfall?
Banks legally cannot release thousands of dollars in cash directly to minors under 18 or 21. If you pass away while the beneficiary is a minor, the bank will freeze the funds until the family goes to court to establish a formal, legal guardianship or asset conservatorship.
14. Are POD payouts subject to income or inheritance taxes?
The transfer of cash itself isn’t treated as standard income for the beneficiary, but the account assets may be subject to state inheritance taxes, federal estate taxes, or final death duties depending on your local region and the total valuation of the estate.
15. How can I transform my regular bank account into a POD account?
You simply need to notify your financial institution. You can do this by visiting a local physical branch or accessing your online banking platform to complete a Beneficiary Designation Form, filling in the full legal name, date of birth, and identity number of your chosen heirs.
Final Thought & Message to Customers
“Payment on Death is a simple instruction that ensures your money goes to the right person quickly and legally if anything happens. It reduces delays, costs, and family stress.” It is a small step that makes a big difference and yet one of the simplest most powerful financial planning tools available in Africa & Nigerian banking today. With just a form and proper documentation, you can protect your loved ones from unnecessary delays, legal stress, and financial uncertainty.
In a country where inheritance issues often divide families and drain resources, setting up a POD instruction is not just a banking decision, it is a responsible life decision.
If you have a bank account, the real question is not “Do I need POD?”. It is “Why haven’t I set it up yet?”