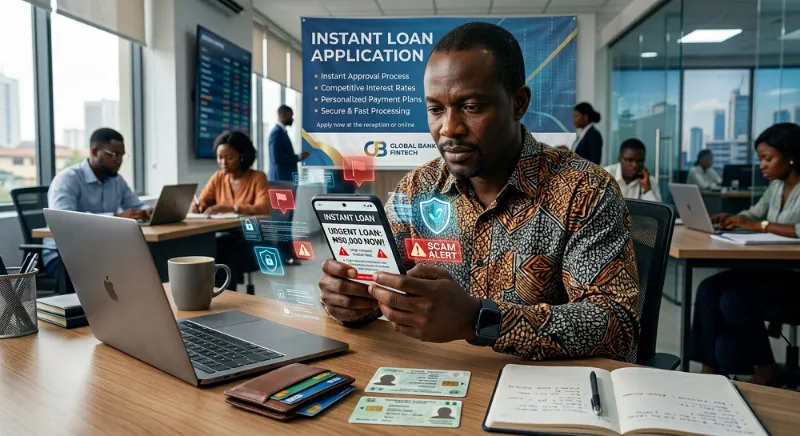
How can you spot a fake loan offers online?
You can spot a fake loan offer by looking for warning signs such as upfront payment requests, guaranteed loan approval, pressure to act quickly, unverified websites, poor communication, and requests for sensitive banking information like passwords or OTPs. Legitimate lenders conduct proper assessments and clearly disclose their terms and fees.
The internet has made borrowing money easier than ever before. Today, people can apply for loans through websites, mobile apps, social media platforms, and digital lending services without visiting a physical branch. While this convenience has helped millions of individuals and businesses access credit, it has also created opportunities for fraudsters to exploit people who urgently need financial assistance.
Fake loan offers are one of the fastest-growing online scams. Criminals understand that people searching for loans are often facing financial pressure, making them more likely to overlook warning signs. These scammers create convincing websites, social media pages, mobile applications, emails, and text messages that appear legitimate. Their goal is simple: steal money, personal information, or both.
Whether you live in Nigeria, another African country, Europe, Asia, or North America, the risk is the same. Fake lenders target students, workers, business owners, job seekers, and even retirees.
Understanding how these scams work can help you avoid becoming a victim.
What Is Fake Loan Offers Online?
A fake loan offer is a fraudulent scheme designed to trick people into believing they have been approved for a loan when no genuine lending service exists.
The fraudster may pretend to represent a bank, microfinance institution, fintech company, online lender, cooperative society, or international financial organization. They often promise quick approval, low interest rates, large loan amounts, and minimal documentation requirements.
Once the victim shows interest, the scammer requests advance payments, sensitive financial information, identity documents, or account credentials.
After obtaining money or information, the fraudster disappears or continues demanding additional payments.
Why Fake Loan Scams Are Increasing
Several factors have contributed to the rapid growth of online loan fraud.
First, digital banking and mobile lending have expanded significantly across Africa and other parts of the world. More people now use smartphones to access financial services.
Second, economic hardship has increased demand for quick financial assistance. Individuals facing urgent expenses may be willing to act quickly without conducting proper verification.
Third, social media platforms allow scammers to advertise fake loan products to thousands of people within minutes.
Finally, advancements in technology make it easier for criminals to design professional-looking websites and applications that appear trustworthy. Fake loan scammers often use stolen identities and forged documents. If you’re concerned that your personal information has been misused, read our guide on what to do if someone creates a fake bank account in your name.
Common Signs of a Fake Loan Offers Online
Recognizing warning signs is the first step toward protecting yourself.
1. Upfront Fees Before Loan Disbursement
One of the biggest red flags is a request for payment before receiving the loan. Fraudsters often claim the payment is needed for:
- Processing fees
- Insurance charges
- Tax clearance
- Registration costs
- Verification fees
- Legal documentation
Legitimate lenders generally deduct approved charges from the loan proceeds or clearly explain their fee structure through authorized agreements. A lender demanding immediate payment before releasing funds should raise serious concerns.
2. Guaranteed Approval Regardless of Credit History
Real lenders assess risk before approving credit. When a company promises approval for everyone without reviewing income, employment status, business performance, repayment ability, or credit history, caution is necessary.
Statements such as:
- “100% Guaranteed Approval”
- “No Questions Asked”
- “Everybody Qualifies”
- “Instant Approval for All Applicants”
are commonly used by scammers to attract desperate borrowers. No legitimate lender can safely guarantee approval to every applicant.
3. Pressure to Act Immediately
Scammers frequently create artificial urgency. They may say:
- “Offer expires today”
- “Pay within one hour”
- “Limited slots remaining”
- “Loan approval will be cancelled”
This pressure is designed to stop victims from performing independent verification. Genuine financial institutions generally provide customers with sufficient time to review terms and conditions before making commitments.
4. Unprofessional Websites and Communication
A fraudulent lender may operate through poorly designed websites or unofficial communication channels.
Watch for:
- Numerous spelling mistakes
- Poor grammar
- Broken website links
- Missing company information
- Generic email addresses
- Lack of customer support
While website quality alone does not determine legitimacy, multiple inconsistencies should not be ignored.
5. Requests for Sensitive Banking Credentials
Legitimate financial institutions may ask for identity verification documents but should never request confidential security information such as:
- ATM PINs
- Online banking passwords
- Mobile banking passwords
- One-Time Passwords (OTPs)
- Security tokens
Any individual requesting these details is likely attempting fraud.
6. Contact Through Unverified Social Media Accounts
Many scammers aggressively promote fake loans through social media. Although legitimate lenders may maintain social media pages, borrowers should avoid relying solely on information provided through social platforms. Always verify the lender through official channels before submitting personal information.
7. No Physical Address or Regulatory Information
Legitimate financial institutions are usually registered and regulated by appropriate authorities. A lender that cannot provide verifiable registration details, business information, or customer service contact points should be treated with caution. Before applying, ensure the institution can be independently verified.
Digital Loan Verification: How to Spot and Avoid Loan Scams
Is this loan offer real?
How do I know if a loan company is legit?
- Regulatory Registration: In Nigeria, legitimate digital lenders must be approved by the Federal FCCPC (Federal Consumer Protection and Commission) and licensed by the Central Bank of Nigeria (CBN). Check their official registers.
- Physical Address & Contact: Real companies provide a verifiable physical office address, an official corporate website, and a monitored customer support email. They do not operate solely through mobile numbers or Telegram.
- App Store Compliance: Legitimate loan apps are hosted on the official Google Play Store or Apple App Store and comply with strict privacy policies—meaning they will not request access to your entire contact list or gallery.
What are the signs of a fake loan?
- Guaranteed Approval: They promise to give you money even if you have terrible credit, no income, or no collateral, without performing any identity checks.
- High-Pressure Tactics: The “agent” creates a false sense of urgency, claiming the offer expires in a few hours if you do not lock it in immediately.
- Unprofessional Communication: The messages contain poor grammar, spelling mistakes, or originate from public email addresses (like
@gmail.com) instead of a secured corporate domain. - Shady Digital Practices: The loan app demands invasive phone permissions (like reading your SMS and contacts) to blackmail you later.
Can lenders ask for upfront fees?
How do online loan scams work?
- The Bait: Scammers launch highly targeted social media ads, send spam text messages, or publish fake loan apps offering low-interest loans with instant approval.
- The Hook: The victim applies, and the scammer quickly approves the loan to build false trust.
- The Advance-Fee Demand: Before releasing the funds, the scammer claims the borrower must pay an upfront fee (e.g., a “security deposit” or “tax validation fee”). Once paid, the scammer vanishes with the money.
- The Predatory App Trap (Alternative): If using a malicious app, the lender might actually disburse a tiny fraction of the money but charge exorbitant, illegal interest rates (e.g., 100% in 7 days). If the borrower is even an hour late, the app uses scraped phone contacts to defame, harass, and threaten the victim’s friends and family.
How Fake Loan Scammers Operate
Understanding their tactics helps you recognize threats earlier.
The Advance Fee Scam
This is perhaps the most common loan fraud model. The scammer claims your loan has been approved and requests a small processing fee. After payment, they demand additional charges. The cycle continues until the victim realizes the loan never existed.
Identity Theft Scheme
Some criminals focus on collecting personal documents rather than money. Victims may be asked to submit:
- National ID cards
- Driver’s licenses
- Utility bills
- Passport photographs
- Bank statements
These documents can later be used for identity theft, account fraud, or other criminal activities.
Fake Loan Applications
Fraudsters may create realistic loan applications resembling those used by genuine institutions. The goal is to harvest personal and financial information for future exploitation.
Mobile App Loan Scams
Cybercriminals increasingly publish fake lending apps that imitate legitimate lenders. Users install these apps and unknowingly provide access to contacts, messages, photos, and personal information. In some cases, scammers use the information for blackmail or harassment.
How to Verify a Loan Provider
Before accepting any loan offer, conduct proper due diligence.
Research the Institution
Search for independent reviews, customer experiences, and publicly available information about the organization. A complete absence of information deserves attention. Legitimate lenders typically have a visible business presence and a history that can be traced.
Visit Official Websites
Avoid clicking suspicious links received through unsolicited messages. Instead, search independently for the institution’s official website and contact information.
Confirm Registration Status
In Nigeria, borrowers should ensure the lender operates legally within the country’s regulatory framework. Likewise, borrowers in other African countries and global markets should verify that the lender appears on the appropriate regulatory registers where applicable.
Contact Customer Support
Call or email the lender directly using verified contact details. Ask questions about loan terms, fees, repayment schedules, and business registration. Fraudsters often struggle to provide consistent answers.
Read the Loan Agreement Carefully
Never accept a loan without reviewing the full agreement. A legitimate lender should clearly disclose:
- Interest rates
- Repayment periods
- Penalties
- Fees
- Borrower obligations
Vague or secretive terms represent a significant warning sign.
What to Do If You Suspect a Loan Scam
If you encounter a suspicious loan offer, avoid making payments or sharing additional information. Take the following actions:
Stop Communication
Cease contact immediately once you identify warning signs. Avoid replying to messages or answering calls from suspected scammers.
Preserve Evidence
Save screenshots, emails, text messages, loan advertisements, and transaction records. These may be useful during investigations.
Notify Your Bank
If you have transferred money or disclosed sensitive financial information, inform your bank immediately. Early reporting may help reduce potential losses.
Change Compromised Passwords
If online banking credentials or financial account details were exposed, update them without delay.
Report the Scam
Victims should report suspicious activities to relevant law enforcement agencies, financial regulators, consumer protection authorities, or cybercrime units within their respective countries. Reporting helps authorities identify patterns and protect other potential victims.
How to Protect Yourself Fake Loan Offers Online
The best defense is prevention. Develop the habit of:
- Verifying lenders independently
- Reading reviews carefully
- Avoiding upfront payment requests
- Ignoring unrealistic promises
- Protecting personal information
- Using only established financial institutions
- Reviewing loan agreements thoroughly
Most importantly, remain cautious whenever a loan offer appears too good to be true. Fraudsters rely on emotions such as desperation, excitement, urgency, and trust. Taking time to verify information can prevent financial losses and identity theft.
How to Recover Your Digital Footprint If You Already Downloaded a Fake Loan App
- Revoke App Permissions Instantly: Go to your smartphone’s Settings > Apps > Permissions. Select the fraudulent app and manually toggle off access to your Contacts, Storage/Gallery, SMS, Location, and Call Logs.
- Uninstall the App and Clear Cache: Clear the app’s data and cache within your settings before clicking Uninstall. If you downloaded the app via an unverified APK file link from WhatsApp or Telegram, ensure you delete the raw source file from your phone’s “Downloads” folder.
- Alert Your Contact List Proactively: Do not wait for scammers to send defamatory text messages to your friends, family, or coworkers. Send a broadcast message or social media update stating: “My phone data was compromised by a malicious financial app. If you receive any threatening or defamatory messages regarding me, please ignore, block, and report the number.”
- Change Your Critical Passwords: Since these malicious apps scan background activities, immediately update the passwords and multi-factor authentication (MFA) parameters for your primary email addresses, mobile banking platforms, and social media profiles.
- File an Abuse Report with Regulatory Authorities: Report the predatory behavior directly to the regulator. Send your evidence, including screenshots of threats and the app name, to the Federal Competition and Consumer Protection Commission (FCCPC) dedicated task force via email at lenderstaskforce@fccpc.gov.ng. If you face criminal intimidation, file a cyber-harassment petition with the Nigeria Police Force Cybercrime Center (NPF-CC)
Official Registers: Only Use FCCPC Approved Digital Lenders
- Check the comprehensive, updated register of licensed digital financial platforms on the official FCCPC Digital Money Lenders Portal.
- Review the specific catalog of fully authorized operational applications using the FCCPC Approved DML List Database.
- Verify compliant network infrastructure service providers on the FCCPC Approved Airtime and Data Lenders Registry.
Frequently Asked Questions (FAQs)
Can a legitimate lender ask for money before disbursing a loan?
Legitimate lenders may disclose fees, but borrowers should be cautious when asked to make upfront payments before receiving approved funds.
Are loan offers on social media safe?
Not all loan advertisements on social media are legitimate. Always verify the lender through official channels before applying.
What happens if I submit personal information to a fake lender?
Your information may be used for identity theft, fraud, unauthorized account access, or other criminal activities.
How do fake loan websites look real?
Scammers often copy branding, logos, website layouts, and content from genuine financial institutions to appear legitimate.
Can online loan scams affect people outside Africa?
Yes. Loan scams operate globally and target victims in both developing and developed countries.
Conclusion
Fake loan offers have become a global problem affecting borrowers in Nigeria, across Africa, and around the world. As digital lending continues to expand, scammers are developing increasingly sophisticated tactics to deceive unsuspecting individuals.
Fortunately, most loan scams share common warning signs. Requests for upfront fees, guaranteed approvals, pressure tactics, unverified websites, and demands for sensitive security information are among the clearest indicators of fraud.
Before accepting any loan offer, verify the lender’s legitimacy, read all terms carefully, and seek independent confirmation where necessary. A few extra minutes of research can save you from significant financial loss, identity theft, and emotional distress.
When it comes to borrowing money online, caution is not paranoia. It is smart financial protection.
Disclaimer: This article is for informational and educational purposes only and does not constitute formal legal or financial advice.