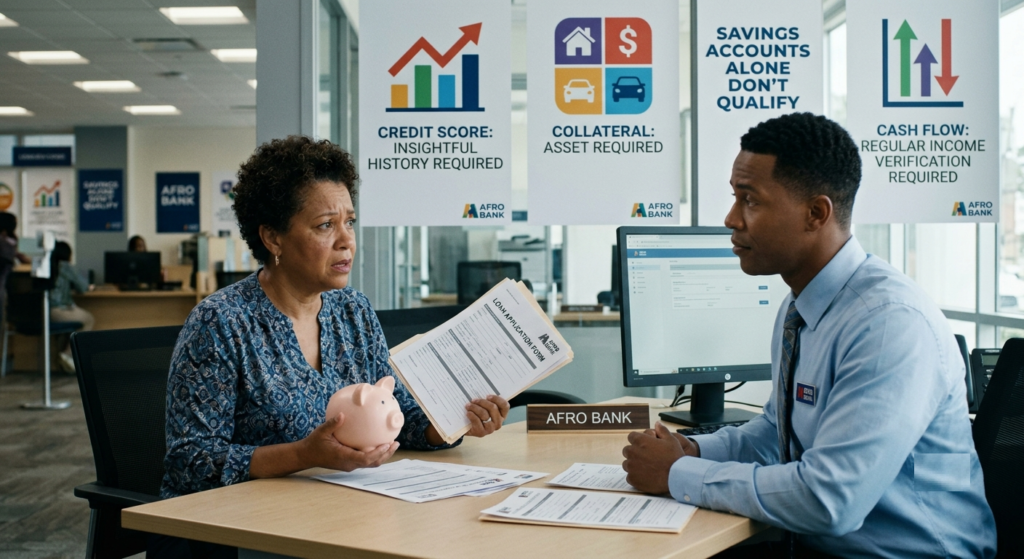
Banks do not issue loans directly to or against standard personal savings accounts because these accounts inherently fail to provide the collateral security and structured financial transparency that lenders require to mitigate risk. Standard savings accounts are fluid, allow unrestricted withdrawals, and rarely reflect a predictable income stream.
Many people assume that having a savings account automatically qualifies them for a loan but do not know the reasons for loan rejection. After all, if you’ve been saving diligently, shouldn’t the bank reward you with easy access to credit? The reality is more complex. Banks operate under strict financial rules and risk assessments, and personal savings accounts alone don’t meet the requirements for loan approval. This article explores the reasons behind this, the principles guiding banks, and what you can do to improve your chances of securing a loan.
Structural Reasons Why Banks And Financial Institutions Don’t Give Out Loan To Personal Savings Account
1. Lack of Verifiable Cash Flow
- Unpredictable Deposits: Unlike checking or salary accounts, savings accounts often show erratic, irregular, or one-off deposits rather than consistent monthly inflows.
- No Income Verification: Lenders rely heavily on steady cash flow to calculate your debt-to-income (DTI) ratio. A savings account proves you can hold money, but it doesn’t prove a recurring, stable income to cover long-term monthly loan installments.
2. High Liquidity and Lack of Collateral Security
- Fluid Asset Structure: Money in a traditional savings account can be withdrawn at any given time via ATMs, mobile apps, or transfers. Because the balance is volatile, banks cannot safely consider it an asset to protect against a default.
- Unsecured Nature: Unless you explicitly sign up for a specialized product where your savings are legally “frozen” or locked by the bank (such as a cash-backed or passbook loan), a normal savings balance provides zero collateral value.
3. Red Flags on Bank Statement Health
- Irregular Balances: If a review of your savings statements exposes highly inconsistent balances or patterns of draining the account to zero, it signals weak financial health and a low capacity to handle debt.
- No Overdraft Safeguards: Savings accounts generally lack the operational overdraft features or credit history tracking associated with transaction-heavy checking or current accounts.
Viable Alternatives to Secure a Loan
- Salary or Current Account Conversion: Move your primary transactions or salary deposits to a transactional checking/current account to establish a visible paper trail of steady income.
- Secured Cash-Backed (Passbook) Loans: Ask your bank for a Bank rate “passbook loan” or a secured personal loan. The bank will lock an exact portion of your savings as collateral in exchange for low-interest credit, while your remaining funds continue to earn interest.
- Build a Strong Credit Score: If you want an unsecured personal loan, prioritize building an independent credit history via specialized credit products or minor credit cards. This shifts the bank’s assessment from your immediate account balance to your proven repayment track record.
Understanding the Purpose of a Savings Account
A savings account is designed primarily for depositing and storing money safely, not for borrowing. Its main functions include:
- Encouraging financial discipline.
- Providing interest on deposits.
- Offering liquidity for emergencies.
While it shows that you value saving, it doesn’t demonstrate your ability to repay borrowed funds. Banks need more than proof of savings; they need evidence of consistent income and repayment history.
Understanding Reason For Loan Rejection To Personal Savings Account
Loans Are About Risk, Not Just Money
Banks are risk managers. Every loan is a calculated gamble: will the borrower repay or default? To minimize risk, banks rely on:
- Credit scores to measure repayment history.
- Collateral to secure the loan.
- Income verification to ensure repayment ability.
A savings account balance doesn’t provide these assurances. Even if you have ₦1,000,000 in savings, the bank cannot assume you’ll repay a ₦500,000 loan without default.
Savings Accounts Lack Collateral Value
Collateral is an asset pledged to secure a loan. Examples include property, vehicles, or fixed deposits. A savings account, however, is fluid, money can be withdrawn anytime. Unless you agree to a secured loan (where your savings are “frozen” against the loan), banks cannot treat it as collateral. This flexibility makes savings accounts unsuitable for loan security.
No Proof of Cash Flow
Banks want to see consistent inflows of money. Salary accounts or business accounts demonstrate regular deposits, which signal repayment capacity. A savings account may show occasional deposits, but it doesn’t prove steady income. Without cash flow evidence, banks hesitate to lend.
Creditworthiness Is Measured Differently
Creditworthiness involves:
- Credit score: A numerical measure of borrowing history.
- Debt-to-income ratio: How much debt you carry compared to your income.
- Repayment history: Past loans and how you handled them.
Savings accounts don’t provide this data. Even with a large balance, banks still need proof of responsible borrowing and repayment behavior.
Regulatory and Risk Management Policies
Banks operate under strict regulations to avoid bad loans. Granting loans based solely on savings accounts would expose them to high default risks. Regulatory bodies require banks to follow structured loan processes, including credit checks and income verification. This ensures financial stability and protects depositors’ funds.
The Psychology of Lending
From a psychological standpoint, banks view loans as trust-based agreements. Trust is built on evidence: repayment history, collateral, and income. A savings account shows discipline but doesn’t prove trustworthiness in borrowing. Banks prefer lending to customers who have demonstrated repayment ability, not just saving habits.
Exceptions: When Savings Accounts Can Help
While savings accounts don’t directly qualify you for loans, they can indirectly help:
- Secured loans: You can pledge your savings as collateral.
- Improved creditworthiness: A healthy savings balance shows financial discipline, which may strengthen your loan application.
- Emergency loans: Some banks offer small overdrafts linked to savings accounts.
These exceptions are limited and usually involve freezing or restricting access to your savings.
Alternatives to Using Savings Accounts for Loans
If you want to secure a loan, focus on:
- Building a strong credit history by repaying small loans on time.
- Maintaining steady income through salary accounts or business accounts.
- Exploring secured loan options using fixed deposits or assets.
- Improving your debt-to-income ratio by reducing existing debts.
These strategies carry more weight than a savings account balance.
Practical Example
Imagine two customers:
- Customer A has ₦2,000,000 in a savings account but no credit history.
- Customer B has ₦500,000 in savings, a steady salary account, and a history of repaying loans.
Banks are more likely to lend to Customer B because repayment ability and trust matter more than raw savings.
Rejection & Eligibility (Why Banks Say “No”)
Why is my bank not giving me a loan / What are the common reasons for a loan being refused?
Banks are risk-averse institutions. If they reject your application, it usually means your risk profile is too high. The primary culprits are poor historical credit scores, an inconsistent or unverified income stream, or having a high Debt-to-Income (DTI) ratio, meaning too much of your current salary is already tied up in paying off existing obligations.
What disqualifies you from getting a loan?
Specific automatic disqualifiers in Nigeria include having an active, unpaid default flagged against your Bank Verification Number (BVN) on the Central Bank’s Credit Risk Management System (CRMS), being an unconfirmed or probationary employee at your workplace, or falling outside the bank’s strict minimum/maximum age requirements (typically 18 to 60 years old).
Can banks refuse to give you a loan?
Yes, banks can absolutely refuse to give you a loan. Commercial and microfinance lenders are private or public corporate entities, not public utilities. They are legally permitted to establish their own risk boundaries and decline any application that fails to meet their internal underwriting standards.
Why would a bank deny a savings account?
While rare compared to loan rejections, a bank will deny opening a savings account if you fail to provide valid Know Your Customer (KYC) documentation, such as an unverified National Identification Number (NIN) or a faulty address check. They will also refuse individuals flagged on anti-money laundering (AML) or fraud watchlists.
Strategy, Savings, & Smart Borrowing
Can I get a loan against my savings account?
Yes, this is known as a cash-backed or asset-backed loan. If you have money in a fixed deposit or a high-yield savings account, banks will readily lend you up to 70%–80% of that value. The bank holds your savings as collateral. Because there is virtually zero risk for the lender, these loans are approved almost instantly and feature heavily discounted interest rates.
Can I put a loan in a savings account?
You can, but it is financially counterproductive. Loans accumulate high interest rates (e.g., 25%–35%+ per annum), while savings accounts pay very low interest (often 4%–7%). Leaving borrowed money sitting in a savings account means you are actively losing money every day to the interest rate spread.
What’s the downside of a savings account?
The main downside is that regular savings accounts rarely beat inflation. Your money loses purchasing power over time. Furthermore, under Nigeria’s Global Standing Instruction (GSI) mandate, if you default on a loan at any bank, lenders have the legal right to automatically pull funds directly out of your savings accounts across the entire banking ecosystem to clear your debt.
What is the smartest way to borrow money?
The smartest way to borrow is to use a cash-backed loan or secure a line of credit where the funds are directly tied to an appreciating asset or a business project that yields a higher return than the cost of the loan’s interest.
Is it better to use savings or get a loan?
If you are purchasing a depreciating asset (like a personal car, electronics, or clothes), it is always better to use savings to avoid high interest. If you are funding a business turnaround or a project with a guaranteed, high-margin cash inflow, it is better to take a loan to keep your liquid safety net intact.
How do I know if my bank will give me a loan?
You can test your eligibility by checking your pre-qualified status on your bank’s mobile application or via their dedicated USSD banking codes. If your account statement shows clean, recurring monthly salary deposits for at least 3 to 6 consecutive months without any failed transactions or overdraft defaults, your probability of approval is high.
What to do if the bank rejects a loan?
First, request a breakdown of the rejection reason. Next, pull your free credit report from a registered credit bureau to ensure there are no false historical defaults attached to your BVN. Focus on cleaning up small, outstanding quick-loans, increase your monthly account activity, or pivot to collateralized borrowing options.
Who will give me a loan if no one else will?
If major traditional commercial banks reject you, licensed digital microfinance banks (Fintechs) and peer-to-peer lending platforms are your next alternative. Because they utilize AI and smartphone data algorithms to score risk rather than relying solely on traditional collateral, they accept higher-risk profiles, though they charge higher interest rates to compensate.
Nigerian Lending Channels (Fastest & Easiest Approvals)
Which bank can easily give a loan / Which Bank is most likely to approve a personal loan?
Digital-first microfinance institutions like FairMoney and Branch are statistically the most likely to approve personal loans because their underwriting structures are fully automated and designed around micro-credit limits that scale upward as you prove your reliability.
Which Bank will give an immediate loan / Which loan is very easy to get?
Unsecured digital payday loans are the easiest and fastest to acquire. For instance, commercial alternatives like Access Bank’s QuickBucks or Stanbic IBTC’s EZ Cash provide instant disbursements directly to your mobile app within minutes if you possess an eligible, salary-mapped history with them.
Which Bank in Nigeria gives loans easily without collateral or complex documentation?
Fintech neobanks like FairMoney, Opay, Palmpay, and Carbon grant emergency credit strictly based on your BVN, NIN, and smartphone data footprint without needing paper documentation or physical collateral assets.
What is the best bank to get approved for a personal loan?
For traditional salary-earners, Stanbic IBTC or Access Bank offer the smoothest institutional approval tracks. For non-salary earners, freelancers, and small traders, digital platforms like Renmoney or FairMoney deliver higher approval probabilities.
Which bank gives the lowest loan?
If “lowest” refers to the lowest interest rates, traditional commercial banks (like Zenith, GTBank, or UBA) provide significantly lower interest rates (often 2.5% to 4% monthly) compared to fintech apps. However, they enforce much stricter approval metrics. If “lowest” refers to the smallest amount, digital apps like Branch allow users to borrow micro-amounts as low as ₦2,000 to ₦5,000 to help them establish their initial credit history.
Frequently Asked Questions (FAQs)
Why is my bank not giving me a loan?
- Active BVN/CRMS Flags: Unpaid debts or defaults on small lending apps reported to the Central Bank’s Credit Risk Management System.
- Lack of Salary Domiciliation: Not routing your monthly salary through the lending bank for at least 3 to 6 consecutive months.
- Employment Unconfirmation: Being a contract worker, a probationary staff member, or working for an unlisted corporate employer.
- Incomplete Documentation: Mismatched details between your National Identification Number (NIN), Bank Verification Number (BVN), and account statements.
Can banks legally refuse to give you a loan?
What instantly disqualifies you from getting a loan?
Can I get a loan against my savings account?
- Use your savings if you are buying a depreciating consumer asset (like a phone, television, or household furniture) to avoid burning money on high interest fees.
- Take a loan if you are financing an appreciating asset, an emergency medical bill, or a business inventory cycle where the projected profit margin is higher than the interest cost of the credit line.
What is the downside of keeping money in a savings account?
Is it smart to put a loan disbursement inside a savings account?
Which bank in Nigeria gives loans easily without collateral?
Which commercial bank will give an immediate payday loan?
What should I do if a bank rejects my loan application?
- Request the rejection reason from your account officer to identify the exact internal metric you failed to meet.
- Pull your free annual credit bureau report to check your BVN history for old, mismanaged, or erroneously recorded micro-loans.
- Clear off all outstanding digital utility or credit app balances and channel your consistent income transactions into a single account for 90 days before reapplying.
Conclusion
Savings accounts are essential for financial stability, but they don’t automatically qualify you for loans. Banks prioritize risk management, collateral, cash flow, and creditworthiness over savings balances. To improve your chances of securing a loan, focus on building a strong credit history, maintaining steady income, and exploring secured loan options.