-
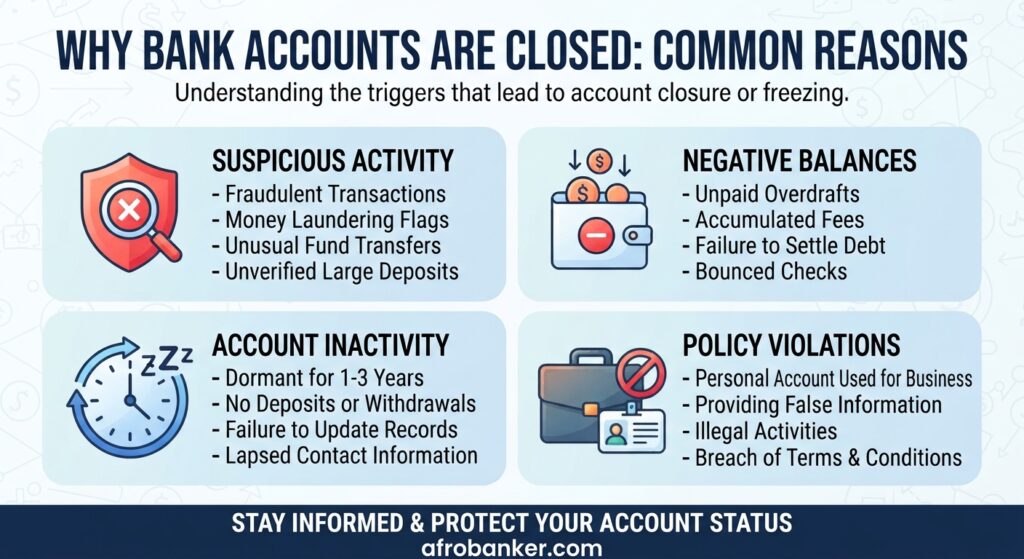
- Unusual transaction patterns: Sudden, large cash deposits or rapid, frequent transfers that do not match your normal banking history.
- Links to fraud or scams: Receiving money from an account that was recently reported for cybercrime, peer-to-peer (P2P) trading fraud like crypto trading, or unauthorized transfers.
- Identity and KYC mismatches: Outdated or unverified personal details, such as mismatched BVN, NIN, or missing valid identification.
- Law enforcement or court orders: Directives from regulatory bodies or authorities (like the EFCC or CBN) ordering a temporary hold or Post-No-Debit (PND) status while they investigate a case.
Discovering that your bank account is under investigation can instantly send a wave of panic through your day. You go to log into your mobile banking app, check your balance, or swipe your card at a store, only to find a locked account, an unexpected restriction, or a notice that your money is on hold.
If this happens to you, the most important thing to know right away is that you are not alone, and an account investigation does not automatically mean you have done something illegal.
Banks operate under strict international regulatory frameworks, such as AML/CFT (Anti-Money Laundering and Countering the Financing of Terrorism) rules enforced globally by institutions like FinCEN in the US, the FCA in the UK, and central banks worldwide to protect money, prevent fraud, and keep financial systems safe. When automated systems or compliance teams notice unusual activity on an account, safety protocols kicks in immediately…
In this article, as a bank insider, I’ll explain exactly why banks place holds on accounts, what algorithms trigger these reviews, and how you can work with your bank to restore your access quickly.
Why Do Banks Investigate Accounts?
Banks don’t freeze or review accounts just to cause headaches; they are legally mandated by global financial oversight bodies to monitor transactions continuously. Whether governed by FinCEN guidelines in North America, FCA regulations in the UK/Europe, or local authorities like the Central Bank of Nigeria to monitor transactions and flag anything that seems out of the ordinary. Every licensed financial institution must adhere to strict AML (Anti-Money Laundering) and KYC (Know Your Customer) protocols.
Every account has a “normal profile” based on how it is typically used. If your account usually handles routine cheque payment and everyday living expenses, a sudden change in patterns sends a signal or a suspicious transaction to the bank’s security monitoring system or their compliance team.
Common Reasons an Account Gets Flagged
-
Sudden Large Deposits or Wires: Receiving a large sum of money, especially from an unfamiliar source or an international sender, can trigger an automated check.
International Transfer Note: Cross-border transfers above certain thresholds (such as $10,000 USD in the United States or €10,000 in Europe) automatically generate regulatory reporting flags under FinCEN, FCA, or FATF guidelines. Many international wire holds are simple, routine compliance checks rather than fraud freezes.
-
Rapid Transfers (High Velocity): Money moving in and out of your account almost instantly can look like automated activity or a pass-through setup, which security teams review carefully. For example, my bank compliance team can put an account on hold when huge amount of money enters the account, and at that instance, the receiver tries moving same amount out to another account.
-
Unusual Cash Deposits: Frequent cash deposits, especially in large amounts, naturally draw scrutiny because cash is difficult to trace.
-
Splitting Transactions ( Deposit Structuring): Making several smaller cash deposits over a short period to avoid standard reporting limits is against banking regulations and triggers an immediate compliance review. To learn more about how cash deposit patterns affect account standing, see our detailed guide on how staff-driven deposit structuring impacts compliance.
-
Using a Personal Account for Business: If a personal checking account receives dozens of payments from different customers or third parties, the bank may pause the account to verify whether it is being used for unauthorized commercial operations.
Understanding how banks manage operational security and protect account holders can give you a clearer picture of these internal checks. For a deeper look at institutional security measures, explore our insights on ATM security protocols and fraud protection.
What Happens During a Bank Investigation?
When an account is flagged, the bank follows a step-by-step review process to determine if everything is legitimate:
-
The Automated Flag: An algorithm detects an unusual pattern and sends an alert to the risk management and compliance team especially with the help of AI driven tool.
-
The Administrative Hold: To protect funds while reviewing the situation, the bank may temporarily restrict certain actions, like outgoing wire transfers or ATM withdrawals.
-
Internal Review: A compliance officer looks at your transactional history and compares it to your account history and provided profile information.
-
Document Request: If more context is needed, the bank contacts you to request proof of funds or explanatory paperwork. This is where KYC, EDD is required.
-
Resolution: Once the origin and purpose of the funds are verified, the hold or lien is lifted and full account access is restored.
How long does a bank account investigation take?
Most internal bank reviews take anywhere from a few business days to a couple of weeks, depending on how quickly you provide requested documents and the complexity of the transactions being reviewed. (e.g., Routine flags: 24–72 hours; AML/KYC verification: 7–14 business days)
What to Do If Your Account Is Under Review
If your account has been restricted or placed under investigation, remaining calm and taking organized action is the best path forward. Overtime, as a bank staff, I have seen our customers panicking when their accounts is placed on lien or hold. This is not the best approach towards the issue.
1. Contact Your Bank Directly
Reach out to your bank’s customer service or security team right away. Ask to be connected with the fraud or compliance unit handling your case. Keep communications clear, polite, and cooperative.
2. Prepare Relevant Documents
Depending on what triggered the flag, gather documentation that proves the origin and purpose of the funds:
-
For a property or asset sale: Sales agreements or closing paperwork.
-
For an inheritance or gift: A legal letter, court document, or transfer record.
-
For business payments: Invoices, contracts, or receipts.
-
For employment or freelance earnings: Pay cheques, statement of account, tax records, or client agreements.
3. Maintain Complete Transparency
Be fully honest about where the money came from and why the transaction took place. Providing clear explanations alongside matching documents helps compliance officers clear flags quickly.
Can I Still Receive My Monthly Salary/Paycheck If My Account is Under Investigation?
What Happens to Pending Automated Bills and Direct Debits When an Account is Frozen?
Can the bank legally keep my money if they close my account?
• “Will a bank freeze on one account affect my accounts at other banks?”
Why is my bank account under investigation out of nowhere?
Does an account review mean I am in trouble or under criminal investigation?
Can a bank freeze your account without telling you
-
- Velocity: Receiving large sums of money and immediately transferring them out within minutes.
- Structuring: Intentionally breaking down a large cash sum into multiple small deposits to evade regulatory reporting thresholds.
- Profile Mismatches: A massive influx of funds on an account historically used only for low-value daily retail purchases.
How do I know if my bank account is being monitored
Can my account get frozen for doing crypto P2P trading?
What happens if I accidentally receive scammed or fraud money?
Why did Zelle/Venmo/Cash App trigger a security hold on my bank?
What documents do I need to prove the source of my funds to the bank?
-
- For employment or freelance: Official payslips, an employment contract, or a signed letter of engagement.
- For business sales: Signed corporate invoices, delivery receipts, clear chat logs with the customer, or a registered business license.
- For asset sales: A signed deed of assignment, a vehicle bill of sale, or official court probate documents for inheritances.
How do I write an appeal letter to unfreeze my bank account?
-
- Header: Address it directly to the “Compliance and Fraud Risk Department” of your specific bank branch.
- Identification: Clearly state your full official name, account number, BVN/identity numbers, and linked phone number.
- The Core Request: State that you are writing to formally appeal the current restriction (PND/Freeze) placed on your account.
- Transaction Clarification: Explicitly reference the date, amount, and reference number of the specific transaction that triggered the flag. Explain its exact purpose.
- Attachments: List your attached pieces of evidence (invoices, receipts, valid ID card) and state your absolute willingness to cooperate with their audit.
What is the difference between a temporary hold, a PND, and a closed account?
-
- Temporary Hold: A brief, automated pause on a single transaction or your entire account—usually lasting 24 to 72 hours—while the bank verifies your identity or a specific check.
- Post-No-Debit (PND): A severe compliance or court-ordered freeze that allows deposits to enter your account but strictly blocks all outward transfers, withdrawals, and debit card usage.
- Closed Account: The ultimate termination of the banking relationship. The bank permanently shuts down your profile due to a severe policy violation and cuts off your access to their services entirely.
Can I open a new bank account if my current one is under review for fraud?
How to Prevent Future Account Flags
Preventing account reviews comes down to clear record-keeping and transparent banking habits:
-
Keep Personal and Business Funds Separate: Always use a dedicated business account for commercial activities and client payments.
-
Notify Your Bank Before Large Transactions: If you expect a unusually large wire transfer, inheritance, or property sale payout, give your bank a quick heads-up in advance.
-
Avoid Splitting Cash Deposits: Deposit cash openly in full amounts rather than breaking deposits up over multiple days.
-
Maintain Digital Records: Keep copies of contracts, invoices, and receipts organized so you can easily provide them if ever asked.
By maintaining clear records and understanding how compliance systems work, you can keep your accounts running smoothly and handle any unexpected reviews with confidence.
Frequently Asked Questions (FAQs)
What does it mean when a bank account is under investigation?
When a bank account is under investigation, it means the bank’s compliance or security department is actively reviewing account activity to verify that transactions are legitimate, safe, and in line with banking rules and regulations.
Why is my bank account under investigation?
An investigation is usually triggered by unexpected or unusual activity. This can include sudden large deposits, frequent cash deposits, rapid money transfers, international wires, or using a personal account for business payments.
How long does a bank account investigation take?
Most internal bank reviews take anywhere from a few business days to a couple of weeks, depending on how quickly you provide requested documents and the complexity of the transactions being reviewed.
Can a bank investigate your account without telling you?
Yes. Banks often monitor and review account activity silently behind the scenes. In cases involving legal inquiries or potential security risks, regulatory rules may prohibit the bank from notifying the account holder immediately.
What happens when your account is under investigation?
During an investigation, the bank may place a temporary hold on your funds or restrict certain features, such as outgoing transfers, online banking access, or ATM withdrawals, until the review is complete.
How do I know if my bank account is under investigation?
You may notice declined card transactions, locked online banking access, or pending transfer holds. In many cases, the bank will contact you directly via phone, email, or physical mail asking for additional documentation.
Can I withdraw money if my account is under investigation?
In most cases, withdrawals are temporarily restricted while an account is under review to keep the funds secure. Access is restored once the review process is finalized.
What should I do if my bank account is under investigation?
Contact your bank’s compliance or customer support team immediately to ask what information is needed. Gather relevant financial records, such as pay cheques, account statement, contracts, or invoices, and cooperate fully with their requests.
Can a bank close my account after an investigation?
If the bank cannot verify the source of your funds, suspects fraudulent activity, or determines that the account usage violates their terms of service, they reserve the right to close the account and issue a check for remaining eligible balances.
Will a bank account investigation affect my credit score?
An internal bank investigation alone does not affect your credit score. However, if an account closure leaves an unpaid negative balance that gets sent to a collections agency, that collection entry could impact your credit profile.
Conclusion
Your bank account may be under investigation for reasons ranging from suspicious transactions to regulatory compliance. While frustrating, these measures are designed to protect both you and the financial system. By understanding the pattern and cooperating with your bank, you can resolve issues quickly and prevent future disruptions.