
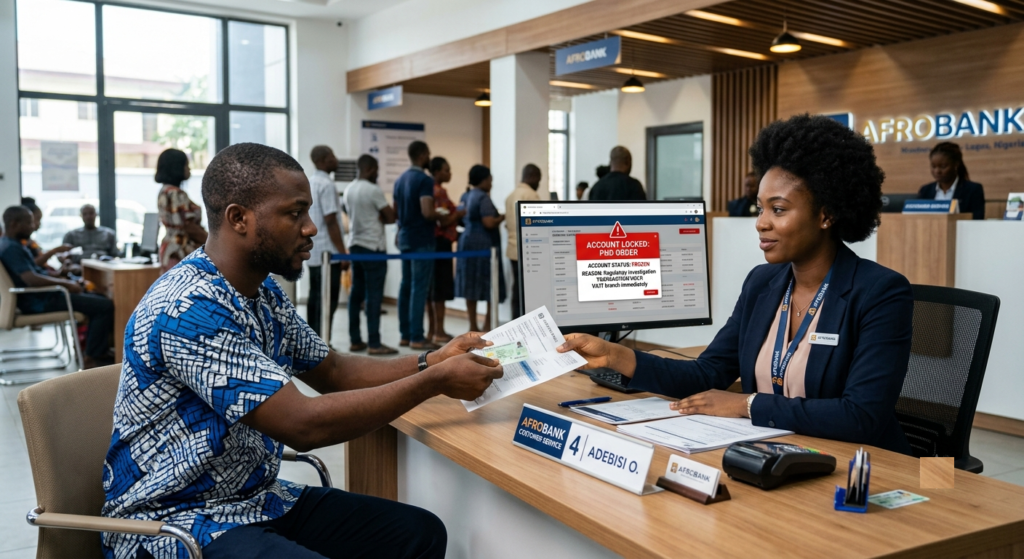
As a bank staff with 10 years plus experience, to clear a Post No Debit (PND) order on your bank account, you must visit your bank branch or contact your account officer immediately to identify the reason for the order, submit required verification or compliance documents (such as KYC updates or proof of transaction legitimacy), or resolve any underlying investigations or court directives.
Step-to-Step Guide to Clearing a PND
- Find the Cause: Contact your bank via customer support, your mobile banking app, or an in-person visit to ask why the PND was placed (e.g., KYC mismatch, flagged fraudulent transaction, or law enforcement directive).
- Submit KYC / Compliance Documents: If the block stems from outdated information, update your Bank Verification Number (BVN), National Identification Number (NIN), utility bill, or valid ID.
- Address Fraud or Dispute Flags: If flagged for a suspicious incoming or outgoing transfer, provide supporting invoices, sender details, or statements proving the legitimacy of the funds.
- Resolve Legal or Agency Holds: If the restriction was ordered by the EFCC, ICPC, or a court, you may need to work with the investigating agency or retain a lawyer specializing in banking law to petition the court or secure a vacation order.
- Track Resolution Timelines:
-
-
- KYC / Profile updates: Usually clear within 24 to 72 hours.
- Suspicious transaction reviews: Often take 1 to 3 weeks.
- Court or law enforcement orders: Can take several weeks to months depending on legal proceedings.
-
Imagine waking up, trying to pay for something, and suddenly your bank app flashes: “Transaction declined-PND order.” Panic sets in. Your money is there, but you can’t touch it. This is the reality for many Nigerians and people globally who find their accounts restricted under a Post No Debit (PND) order. Do not panic as your money isn’t gone but restricted.
A PND order doesn’t mean you’ve done something wrong, it means the bank or regulators need clarity. In this guide as a bank staff member, I will break down what a PND order is, why it happens, and step-by-step strategies to fix it.
What Exactly Is a PND Order and Why is Your Money Trapped?
PND stands for Post No Debit. It’s a restriction placed on your account that prevents any outgoing transactions. You can still deposit money, but you cannot withdraw, transfer, or make payments.
Banks use PND orders to:
- Comply with regulatory directives from the Central Bank of Nigeria (CBN) or EFCC.
- Investigate suspicious transactions.
- Enforce court orders.
- Protect customers from fraudulent activity.
Think of it as a “pause button” on your account until issues are resolved.
Why Do Banks Place PND Orders?
Suspicious Transactions
Large or unusual deposits, especially from unknown sources, often trigger scrutiny. For example, when a customer receives an unusual inflow of ₦10 million into a student’s account and such money leaves the account immediately, our bank’s compliance team suddenly places a PND on the account until the customers explains the source and purpose of inflow.
Regulatory Compliance
Failure to update KYC (Know Your Customer) documents, expired ID, NIN, outdated address, name mismatch or missing BVN, can lead to restrictions.
Fraud Alerts
If your account is suspected of being used in scams, Ponzi schemes, or “money mule” activity, banks freeze it to investigate. Most people uses their bank account to receive fraudulent inflows without knowing the implication.
In some cases, a Post No Debit restriction is mandated by external regulatory bodies (such as the Central Bank of Nigeria, NIBSS, or law enforcement agencies) or triggered by the bank’s internal compliance system due to suspicious transactions. If your account has been flagged for regulatory review, read my complete breakdown on why bank accounts come under investigation to understand the compliance review process
Court or Law Enforcement Orders
As a bank staff member, I have seen numerous times where court orders or police orders were brought to the bank to place a PND on a customers account. Banks must comply with such directives from courts or agencies like EFCC.
Internal Bank Policies
Routine audits sometimes flag accounts for review, especially dormant or high-value accounts.
What Happens During a PND Investigation?
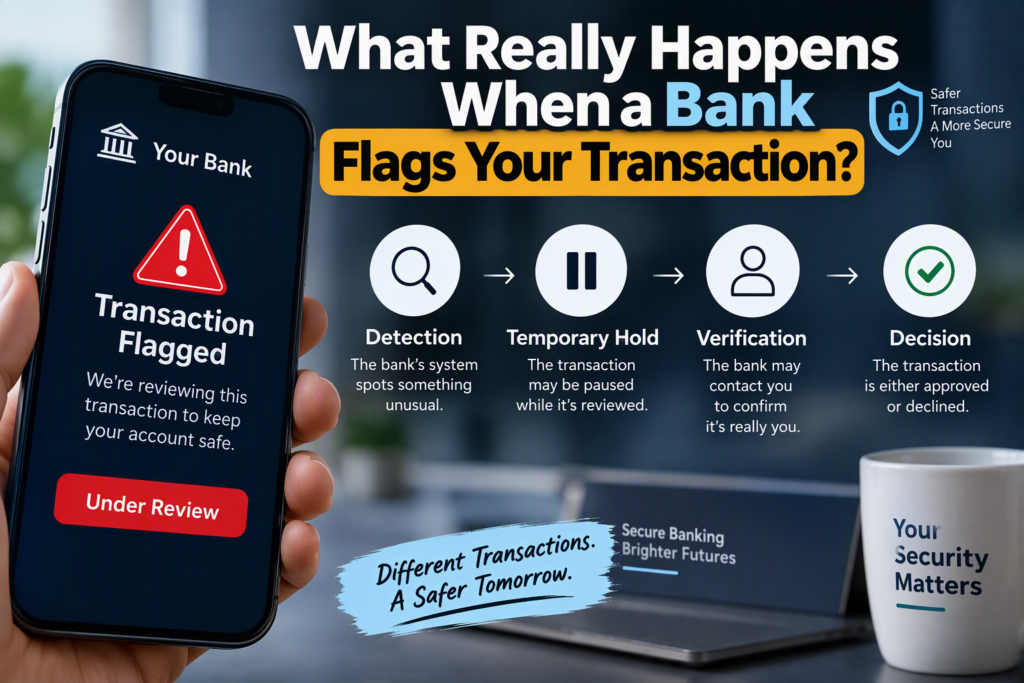
When your account is flagged:
- Debit transactions are blocked but customer can receive inflow
- Bank compliance officers review activity.
- You may be contacted for clarification.
- Regulators may be notified if the issue is serious.
Investigations can last from a few days to several weeks, depending on complexity of the issue and your sincere compliance to the bank.
Step-by-Step: How to Remove a PND From Your Bank Account
Step 1: For Suspicious Transactions, Contact Your Bank Immediately
Go to your bank branch or call your account officer/customer service and ask “Why was your account placed under PND and what documents you need to clear it?” A simple explanation of “source of funds, receipts, invoices, or letters proving the transfer was legitimate will go a long way.
Sample Dialogue:
- Customer: “Good morning, I noticed my account is restricted. Can you explain why?”
- Bank Officer: “Yes, sir. A large deposit was flagged. We need proof of the source of funds.”
- Customer: “I understand. I’ll provide the business invoice and contract today.”
Step 2: Provide Required Documentation for Regulatory Compliance and KYC Issues
Before attempting to lift a PND, you must know what triggered it. Contact customer support or check your banking app notification to see whether it is a routine KYC update issue or a regulatory fraud flag.
Note: If customer support informs you that the hold is due to an active compliance audit, see our detailed guide on why bank accounts are placed under investigation and how to respond.
Providing recent and updated documents like:
- Valid ID (National ID, NIN, Driver’s License, Passport).
- Proof of address (utility bill, tenancy agreement/rent, security levy receipt).
- Evidence of transaction legitimacy (salary slips, business invoices, contracts).
- BVN printout.
- Update expired KYC documents.
- Ensure BVN is linked to your account.
- Cooperate with tax or compliance checks.
Step 3: Seek Legal Support if Necessary
If the PND order is linked to a court case or EFCC investigation, consult a lawyer. Legal motions may be required to lift restrictions. Communicate with your legal team transparently without making things worse so as to avoid delay.
Step 4: Follow Up Consistently
As a bank staff, we handle thousands of cases daily. So a regular follow-up ensures your case isn’t forgotten. Keep records of all communications.
How Long Does it Take for a Bank to Remove PND?
As a bank staff, a realistic operational timeline in removing PND from account varies from the reasons it was placed.
- For KYC updates, it takes up to 24–72 hours.
- Suspicious transactions takes 1–3 weeks.
- Court orders may take months depending on legal teams an swift response.
Therefore, patience and persistence are essential.
How to Prevent Future PND Orders?
- Keep your account information updated.
- Avoid receiving money from strangers.
- Document all large transactions.
- Maintain transparency in business dealings.
- Build a relationship with your bank manager.
Sample Letter to Lift PND From Your Bank Account
[Your Name / Company Name]
[Your Contact Address]
[Your Phone Number]
[Your Email Address]
[Date]
The Branch Manager,
[Bank Name],
[Branch Address].
Dear Sir/Ma,
REQUEST TO LIFT POST NO DEBIT (PND) RESTRICTION ON ACCOUNT NUMBER: (INSERT YOUR ACCOUNT NUMBER)
I am writing to formally request the immediate lifting of the Post No Debit (PND) restriction currently placed on my [Savings / Current / Corporate] account domiciled with your branch.
- Account Name: (Insert Full Account Name)
- Account Number: (Insert 10-Digit Account Number)
- Linked BVN: (Insert BVN Number if necessary)
I was recently informed of the restriction when attempting to perform an outbound transaction. To ensure full compliance with the Central Bank of Nigeria (CBN) regulations and your bank’s internal policies, I have compiled and attached all necessary verification documents required to update and regularize my account profile.
- For KYC / Account Upgrade: I have attached my valid government-issued means of identification, a recent utility bill for address verification, and my updated BVN/NIN details.
- For Sudden Inflows / Source of Funds Flag: I have attached the legitimate invoices, receipts, and contract documents detailing the exact source and purpose of the recent funds deposited into my account.
- For BVN/NIN Name Mismatch: I have attached a certified affidavit of name change, newspaper publication, and marriage certificate to verify the harmonization of my identity records.
I kindly request that your compliance team reviews these attached documents and unfreezes my account to allow me access to my funds for daily operations.
Thank you for your prompt attention to this matter. I look forward to your swift resolution.
Yours faithfully,
[Your Signature]
[Your Full Name]
Enclose:
- Copy of Valid ID Card (International Passport/Drivers License/National ID/NIN)
- Copy of Utility Bill (Not older than 3 months)
- Evidence/Proof of Source of Funds (if applicable)
- Court Affidavit / Newspaper Publication (if applicable)
Note: “Always sign this letter exactly the same way you signed when opening your bank account. A signature mismatch will cause the compliance team to reject your request!”
How to Remove PND on Access Bank, Eco Bank, Fidelity Bank, GTB, First Bank, Heritage Bank, UBA, Polaris Bank, FCMB and Keystone account?
To clear a PND from the above listed bank accounts:
- Visit your nearest branch with a valid regulatory ID (NIN, Driver’s License, International Passport, or Voter’s Card).
- Request an Account Reactivation/KYC Update Form from the customer service desk.
- Provide your current BVN and linking phone number.
- If the PND is due to an irregular transaction flag, ask to speak directly with the branch Compliance/Operations Manager to present your statement of account or proof of funds documentation.
- For security or third-party dispute freezes, you must sign a letter of indemnity or provide concrete evidence that the disputed transaction was authentic before the internal compliance unit will unlock the account.
Take immediate control of the situation by following these final three checkpoints:
- Audit First: Do not guess the root cause; secure explicit confirmation of the specific internal or legal freeze code directly from your financial institution.
- Over-Provide Evidence: Submit clear, unedited paperwork, whether matching updated biometric registration data or providing bulletproof source-of-funds verification invoices.
- Follow Up Relentlessly: Establish an active communication with your assigned account officer to guarantee your documents progress smoothly through compliance processes.
How to remove post no debit on Zenith bank?
To lift a PND from a Zenith Bank account:
- Go to any Zenith Bank branch or email their centralized help desk (zenithdirect@zenithbank.com) using your registered email address.
- For basic KYC/dormancy freezes, present your valid government-issued ID and a recent utility bill (not older than 3 months) to update your profile.
- For security or third-party dispute freezes, you must sign a letter of indemnity or provide concrete evidence that the disputed transaction was authentic before the internal compliance unit will unlock the account.
How can I stop automatic debits from being deducted from my bank account? / How do I stop automatic payments from coming out of my bank?
You can stop recurring automated clearing house (ACH) deductions or standing orders using three primary approaches:
- Revoke the Mandate Online: Log into your internet banking portal, navigate to the “Standing Orders” or “Direct Debits” tab, select the active mandate, and click cancel.
- Notify the Merchant: Contact the service provider billing you and explicitly request them to cancel the recurring billing agreement.
- Issue a Stop-Payment Order: Formally instruct your bank (via email, written letter, or support ticket) to block the specific merchant from drawing funds from your account.
How do I Deactivate Automatic Payment? / How to Stop Online Payment Auto Debit?
To immediately halt card-based online automated debits:
- Open your mobile banking app and navigate to Card Management.
- Look for options labeled “Manage Recurring Payments,” “Tokenized Cards,” or “Web/Online Transactions.”
- Toggle off web transactions entirely, or individually delete the merchant profile linked to your debit card.
How do I Cancel an Automatic Payment Online? / How do I Remove AutoPay From My Account?
- Step 1: Log into the application or website of the merchant charging you (e.g., streaming apps, utility portals, insurance sites).
- Step 2: Go to Billing, Wallet, or Payment Settings.
- Step 3: Click on “Manage AutoPay” or “Linked Cards.”
- Step 4: Select “Remove Card” or “Cancel Subscription.” Always take a screenshot of the confirmation page for your records.
A Comparison Fix Between Post No Debit (PND) and Auto-Debit/AutoPay
| Financial Issue | Primary Trigger | Easiest Online Fix | Mandatory In-Person Fix |
| Post No Debit (PND) | KYC lapse, fraud alert, court order | Digital KYC form upload (some banks) | Legal dispute, biometric mismatch, agency holds |
| Auto-Debit / AutoPay | Active subscription, standing order, card token | In-app subscription cancellation, disabling web pay | Formal written stop-payment indemnity letter |
Frequently Asked Questions (FAQs)
1. Can a bank place a PND without a court order?
Yes. Banks can place a PND order without a court directive if they detect suspicious activity, incomplete KYC records, or regulatory compliance issues. Court orders usually apply in cases of debt recovery or legal disputes, but banks also have the authority to restrict accounts temporarily to protect customers and the financial system.
2. What does “PND” mean in the context of banking?
“PND” stands for Post No Debit. It is a restrictive security order or administrative freeze placed on a bank account by a financial institution or legal authority.
3. Can I still receive money while my account has a PND?
Yes. A PND order only blocks debit transactions. You can still receive deposits into your account, but you won’t be able to withdraw, transfer, or make payments until the restriction is lifted. This is why many customers see their balance grow but remain unable to access funds.
4. How do I check if my account has a PND restriction online?
Most banks will notify you directly through SMS, email, or app alerts. However, you can also:
- Log into your mobile banking app, if transactions fail with “PND restriction,” that’s confirmation.
- Attempt a small transfer, if blocked, the system will display the restriction message.
- Contact customer service via phone or live chat for official confirmation.
5. What is post no debit in banking?
A Post No Debit (PND) order is a banking restriction that blocks all outgoing transactions while still allowing incoming deposits. When active, you cannot withdraw money, transfer funds, pay bills, or use your debit card. However, anyone can still send money into the account.
6. How do I remove PND on my account? / How to remove Post No Debit?
To lift a PND freeze, you must follow these universal steps:
- Contact Your Bank: Reach out to customer care or visit a physical branch to get the exact reason code for the freeze.
- Submit Missing Credentials: If due to KYC issues, complete the data recapture form with valid identification, a utility bill, and your biometrics.
- Prove Source of Funds: If flagged for fraud, provide authentic invoices, business agreements, or sender declarations to prove transaction legitimacy.
- Obtain Legal Clearance: If frozen by a court mandate, engage a legal professional to clear your name with the agency or petition for a vacation order.
7. How do I remove restrictions from my bank account?
To clear generic restrictions (such as spending limits, freezes, or holds):
- Log into your mobile banking app to check if you can toggle the restriction off under Account Settings / Card Control.
- Complete any pending in-app identity verifications (liveness checks or ID uploads).
- Call your bank’s dedicated fraud helpline if your card or account was locked due to entering an incorrect PIN too many times.
8. Why is my account showing post no debit?
Banks apply a PND restriction to your account for several critical reasons:
- KYC Deficiencies: Outdated or unverified personal details, such as missing Bank Verification Numbers (BVN), National Identification Numbers (NIN), or expired IDs.
- Suspicious Activity: Sudden, unusually large inflows or transactional patterns that trigger internal anti-money laundering (AML) fraud flags.
- Dormancy: Extended periods of inactivity on the account.
- Legal/Regulatory Orders: Directives from law enforcement agencies (like the EFCC or ICPC), tax authorities (like the FIRS), or formal court orders resulting from ongoing investigations.
Conclusion
A PND order can be stressful, but it’s not permanent. By understanding why it happens, cooperating with your bank, and providing the right documentation, you can clear the restriction and regain access to your funds. Staying proactive with KYC updates and transparent transactions reduces the risk of future disruptions.
Regaining full control of your finances after a Post No Debit restriction requires prompt, systematic action. While a PND freeze can be incredibly disruptive, remember that banks use this security mechanism to safeguard ecosystem integrity rather than permanently seize asset ownership. Whether the block stems from an expired ID profile, an irregular transfer velocity flag, or an agency compliance directive, the resolution runway relies entirely on transparent cooperation.
Take immediate control of the situation by executing these final three checkpoints:
- Audit First: Do not guess the root cause; secure explicit confirmation of the specific internal or legal freeze code directly from your financial institution.
- Over-Provide Evidence: Submit clear, unedited paperwork, whether matching updated biometric registration data or providing bulletproof source-of-funds verification invoices.
- Follow Up Relentlessly: Establish an active communication log with your assigned account officer to guarantee your documents progress smoothly through compliance queues.
By staying proactive and providing precise, validated evidence to your bank’s compliance team, you can drastically reduce processing latency and successfully restore full transaction capabilities to your account.


Account 1098695561915 marked no debit