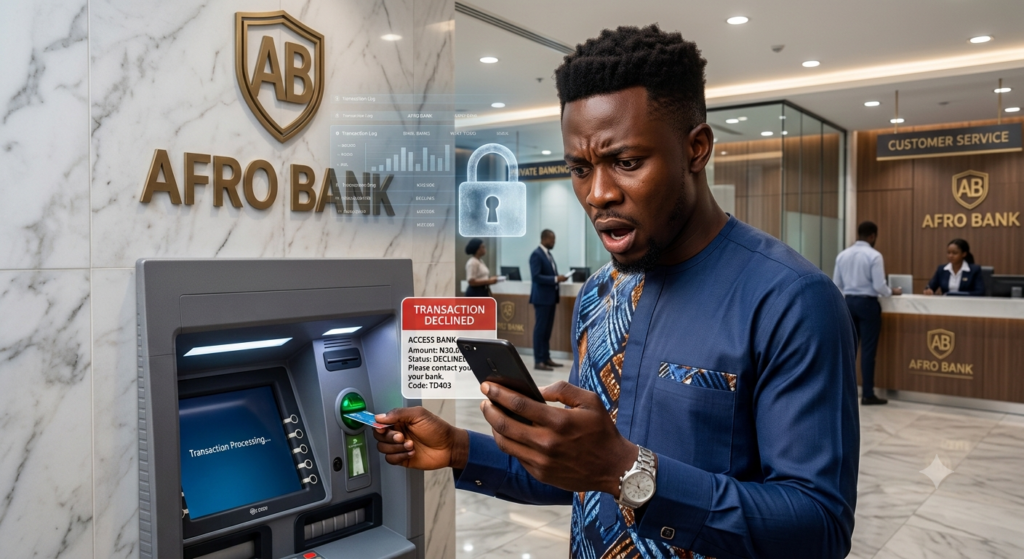
Imagine walking into a store, picking out your items, and heading to the checkout line. You swipe your debit card, fully aware that you have enough funds to cover the purchase. Instead of a receipt, the machine beeps loudly, displaying two words that instantly trigger anxiety, “Transaction Declined.”
You check your mobile banking app, only to find you cannot transfer money, pay bills, or even access your savings.
Having your bank account frozen is a stressful experience that can leave you feeling helpless, stranded, and confused. In today’s digital economy, access to your funds is tied to your daily survival. When that access is cut off, time is of the essence.
Many people discover an account freeze only after a transaction fails.
- Online banking access restrictions
- Card declines despite sufficient balance
- Failed transfers
- ATM transaction errors
- Messages requesting customer verification
- Notifications from the bank regarding account restrictions
What Does It Mean When a Bank Account Is Frozen?
Before diving into the warning signs, it is crucial to understand what a frozen account actually means.
When a bank freezes your account, they place a temporary or permanent restriction on your ability to withdraw or transfer funds out of that account. In most cases, you can still receive incoming deposits, such as your monthly salary or transfers from friends, but the money becomes trapped. You cannot use your debit card, write cheques, make online bank transfers, or withdraw cash from an Automated Teller Machine (ATM).
A freeze is not the same as a closed account. When an account is closed, the relationship between you and the bank is terminated. A freeze, however, is often a protective or legal holding mechanism. The bank is essentially hitting the “pause” button on your finances until a specific issue, dispute, or legal requirement is resolved. To understand if your bank account has been frozen read my complete guide on What Happens When Someone Reports Your Bank Account?
Clear Signs Your Bank Account Has Been Frozen
Banks are legally required to protect user data and comply with financial regulations, which means they do not always send a text message or phone call before a freeze takes place. Often, you will discover the freeze through your own daily financial activities.
Here are the most common indicators that your account has been restricted:
1. Repeatedly Declined Debit Card Transactions
The earliest and most frustrating sign is a declined transaction at a point-of-sale (POS) terminal or an online checkout counter. If you know for a certainty that you have a positive balance, but your card continues to be rejected across multiple merchants, your account may be locked or frozen.
2. Inability to Withdraw Cash from ATMs
When you insert your debit card into an ATM, the machine may spit the card back out, display a “Transaction Prohibited” message, or show an error code indicating that the financial institution has blocked withdrawal capabilities on the card.
3. Error Messages on Mobile Apps and Online Banking Platforms
When you log into your digital banking suite, you might notice an explicit notification. Look out for banners reading:
-
“Account Restricted”
-
“Please contact customer care to update your information”
-
“Transaction failed due to account status”
If your mobile app bars you from moving money to another account or paying utility bills, it is a definitive sign of a restriction.
4. Bounced Cheques and Failed Automatic Payments
If you have set up standing orders or automated clearing house (ACH) payments for your rent, mortgage, or insurance premiums or salaries, these payments will suddenly fail. The bank will refuse to honor the payments, which can result in bounced check fees and penalties from your service providers.
Why Do Banks Freeze Accounts? (Common Triggers)
Banks do not freeze accounts arbitrarily. They operate under strict regulatory frameworks designed to prevent crime, protect consumers, and manage risk. Understanding why your account was flagged is the first step toward fixing the problem.
1. Suspected Fraudulent or Unusual Activity
Financial institutions use advanced artificial intelligence and algorithmic monitoring tools to track your spending habits. If there is a sudden deviation from your normal behavior, the system flags it as potential cyber fraud. Also your account can be frozen if it is reported. If there is a reported deposit structuring in your account, banks may freeze your account for investigation. To understand how banks freezes your account on deposit structuring or splitting my complete guide as a bank staff on Deposit Structuring in Banking: The Hidden Risk Threatening Compliance and Trust will help you not to go against the Nigerian Financial Intelligence Unit (NFIU) rules.
-
Examples: Making a massive international purchase when you have never left your home country, logging into your app from multiple distant IP addresses within minutes, or receiving a massive influx of cash that does not align with your historical account data.
2. Unverified Know Your Customer (KYC) Details
The central banks as regulators require financial institutions to maintain updated, verified records of all customers. If your government-issued identity card expires, or if you fail to update your current residential address or tax identification number when prompted, the bank may place a temporary hold on your account until your profile is brought up to code.
3. Legal Judgments and Debt Collection
If you lose a lawsuit or owe money to creditors (such as credit card companies, medical providers, or private lenders), the creditor can seek a court order to garnish your assets. Once a judgment creditor presents a valid court order to your bank, the bank is legally obligated to freeze the amount owed, plus potential interest and legal fees.
4. Government and Tax Levies
If you have unpaid back taxes or owe government fees, state or national tax authorities have the legal mandate to issue an administrative levy. This bypasses the traditional court system and directly orders your bank to freeze your funds until your tax debt is settled.
5. Suspicion of Illegal Activities (Money Laundering)
Under Anti-Money Laundering (AML) and Counter-Financing of Terrorism (CFT) laws, banks must report and freeze accounts tied to suspected illegal enterprises. If an account frequently transfers funds to high-risk platforms, unverified crypto exchanges, or accounts blacklisted by law enforcement, a hard freeze will be implemented immediately.
How to Resolve a Frozen Bank Account: Step-by-Step Guide
Step 1: Identify the Exact Nature of the Restriction
Do not try to force multiple transactions, as this might trigger additional automated security flags. Instead, take screenshots of any error codes, decline messages, or mobile app notifications you receive. Note down the time, date, and exact amount of the transaction that failed.
Step 2: Contact Your Bank’s Customer Service Immediately
Reach out to your financial institution through their verified channels. You can call the customer care hotline listed on the back of your debit card, use the secure chat feature inside your official mobile banking app, or visit a local physical branch. Speak with with the customer service person, Branch staff, Relationship manager or the Fraud departments.
When speaking to a customer representative, ask the following explicit questions:
-
Why is there a hold or restriction on my account?
-
Is this a security flag, a regulatory compliance issue, or a legal levy?
-
What specific documents or actions are required from my end to lift the freeze?
Step 3: Verify Your Identity/Provide the Necessary Documentation
Many freezes stem from verification concerns. If the freeze is due to a security flag or missing KYC details, the resolution is usually straightforward. You may need to provide:
-
A valid government-issued photo ID (Passport, National ID, Driver’s License).
-
A recent utility bill or proof of residence.
-
Proof of funds (such as an invoice, employment contract, or sales receipt) if a specific large deposit triggered the fraud alarm.
- Phone numbers
- Email addresses
- Residential addresses
- Occupation details
- Business information
- Recent photographs
Step 4: Seek Legal Advice When Necessary
If the bank informs you that your account has been frozen due to a court order, a tax levy, or an ongoing law enforcement investigation, customer support agents will not be able to help you. In these circumstances, you must consult a licensed attorney. A legal professional can help you file an exemption, negotiate a settlement with creditors, or contest an unlawful levy in court.
- Your rights
- Legal obligations
- Available remedies
- Court procedures
Step 5: Cooperate With Fraud Investigations
- Transaction receipts
- Source-of-funds information
- Account statements
- Business records
- Explanations for unusual activity
Step 6: Resolve Outstanding Debt Issues
- Payment arrangements
- Debt restructuring
- Settlement agreements
- Legal resolution processes
How to Avoid Future Account Freezes
My Pro Tip As A Bank Staff
Always maintain financial redundancy. Never keep 100% of your capital in a single bank account. Distribute your liquid funds across at least two independent financial institutions so that if one account faces a temporary operational or regulatory hold, you still have the means to cover your day-to-day living expenses.
Frequently Asked Questions About Frozen Bank Accounts
1. How do I know if my account has been frozen?
The most common signs are declined debit card transactions, failed transfers, blocked withdrawals, restricted online banking access, or a message from your bank stating that your account has been restricted. If multiple transactions fail despite having sufficient funds, contact your bank immediately to confirm your account status.
2. Can I still receive money if my account has been frozen?
In many cases, yes. A frozen account may still be able to receive deposits such as salaries, transfers, or refunds. However, whether you can access or withdraw the funds depends on the reason for the freeze and your bank’s policies.
3. Will the bank tell me if my account has been been frozen?
Usually, yes. Banks often notify customers through SMS, email, phone calls, or online banking alerts. However, in certain situations, such as court orders, fraud investigations, or regulatory directives, a bank may be restricted from disclosing full details immediately.
4. Why would a bank freeze my account?
Banks commonly freeze accounts because of suspected fraud, unusual transaction activity, unresolved Know Your Customer (KYC) requirements, court orders, debt recovery actions, sanctions compliance, or regulatory investigations.
5. Can I withdraw money from a frozen account?
No. A frozen account typically prevents withdrawals, transfers, and debit card usage. The restrictions remain until the issue causing the freeze is resolved or the freeze is officially lifted.
6. How long can a bank account remain frozen?
The duration varies. Some freezes caused by incomplete KYC information can be resolved within days, while legal disputes, court orders, or fraud investigations may keep an account frozen for weeks or even months.
7. What should I do immediately after discovering my account is frozen?
Contact your bank’s customer service or visit a branch immediately. Ask for the reason behind the restriction and the specific documents or actions required to restore access to your account.
8. Can a bank freeze my account without warning?
Yes. If the bank suspects fraud, money laundering, identity theft, or receives a legal directive, it may freeze the account immediately to prevent unauthorized transactions or protect customer funds.
9. What documents might I need to unfreeze my account?
You may be asked to provide a valid means of identification, proof of address, updated KYC documents, transaction evidence, source-of-funds documentation, or any paperwork related to the issue that triggered the freeze.
10. Can online banking still work when my account is frozen?
It depends. Some customers can still log in and view account balances, while others may lose access to certain banking features such as transfers, bill payments, or card management.
11. Is a frozen account the same as a closed account?
No. A frozen account still exists, but access to funds is restricted. A closed account has been permanently terminated and can no longer be used for transactions.
12. Can suspicious transactions cause my account to be frozen?
Yes. Large unexplained deposits, unusual transfer patterns, sudden spikes in activity, transactions linked to known fraud schemes, or inconsistent account behavior can trigger a temporary freeze while the bank investigates.
13. Can my salary be paid into a frozen account?
Yes, in many cases salaries can still be credited to a frozen account. However, you may not be able to withdraw or transfer the money until the freeze is removed.
14. How can I check if my bank account is restricted or frozen?
Try performing a small transfer, ATM withdrawal, or card transaction. If the transaction is declined and you receive messages indicating restrictions or blocked activity, contact your bank to verify whether the account has been frozen.
15. Can a frozen account be reopened or restored?
Yes. Most frozen accounts can be restored once the underlying issue is resolved. This may involve updating KYC records, providing requested documents, clearing legal issues, or satisfying regulatory requirements.
16. Does having a frozen account affect my credit score?
A frozen bank account does not directly affect your credit score. However, if the freeze is related to unpaid debts, loan defaults, or legal judgments, those underlying issues could impact your credit history.
17. Can I transfer money out of a frozen account?
No. Outgoing transfers are usually blocked until the restriction is removed. This includes mobile banking transfers, online payments, standing orders, and ATM withdrawals.
18. Who has the authority to freeze a bank account?
A bank can freeze an account based on its internal risk controls. Courts, law enforcement agencies, tax authorities, anti-corruption agencies, and financial regulators may also direct banks to freeze accounts under specific circumstances.
19. Can a bank freeze a joint account?
Yes. A joint account can be frozen if suspicious activity is detected, legal action affects one of the account holders, or there are compliance concerns related to the account.
20. What is the fastest way to get a frozen account unfrozen?
The fastest approach is to contact the bank immediately, find out the exact reason for the restriction, and submit all required documents without delay. Prompt cooperation often helps resolve administrative and compliance-related freezes more quickly.