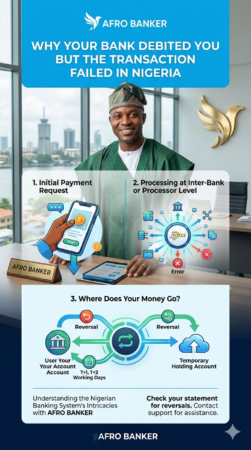
A failed bank transaction with an account debit occurs due to communication timeouts, network congestion, or payment gateway glitches. When this happens, your money is typically held in a secure settlement queue between the sending bank, the payment switch (like NIBSS), and the recipient’s bank.
According to Central Bank of Nigeria (CBN) regulatory timelines, funds from failed same-bank transfers should reverse within 24 hours, while inter-bank transfers, POS, and ATM errors typically reverse automatically within 48 to 72 hours
One of the most frustrating experiences for any bank customer in Nigeria is receiving a debit alert for a transaction that never went through. You try to withdraw cash from an ATM, make a payment through POS or send money via mobile transfer and suddenly your account is debited but the transaction fails. This situation creates panic, confusion, and sometimes anger, especially when the money does not return immediately.
Quick Recovery Steps
- Wait for auto-reversal: Give the system up to 24–72 hours to self-correct.
- Log a dispute: If it exceeds the timeline, submit a “Dispense Error” or “Failed Transfer” form via your bank’s app or customer care channels using your Session ID / Transaction Reference Number.
- Escalate: Unresolved complaints can be formally escalated directly to the CBN Consumer Protection Department via cpd@cbn.gov.ng.
In this comprehensive guide, you will understand why this issue happens in banking, what is happening behind the scenes, how long reversals really takes, what you must do to recover your money and finally how to avoid future failed transactions. This is not theory, this is based on real banking system processes and operations and with my guide on How to Resolve a Failed International Transfer to a Kuda Bank: A Comprehensive Guide Updated October, 2026 you will understand how these failed bank transaction happens and how to manage them.
What Is A Failed Bank Transaction?
A failed bank transaction is a payment attempt that stops midway or does not complete, meaning the intended funds never successfully reach the recipient.
What Happens to the Money?
- Temporary Debiting: Even though the transaction fails, your bank account may still show a deduction. The money is not lost; it is usually stuck in a temporary processing state, a suspense holding account, or a payment switch queue like NIBSS.
- Automatic Reversal: Most failed transactions trigger an automatic refund or reversal back into the sender’s account within a short timeframe (often 24 to 72 hours).
Common Causes of Failure
- Network & System Glitches: Unstable internet connections, mobile app timeouts, or server downtime at the bank or payment switch.
- Incorrect Details: Typing a wrong account number, mismatched billing information, or entering an expired/blocked card.
- Insufficient Funds: Lacking the required balance or exceeding daily transaction limits.
- Security & Fraud Triggers: Bank or card issuer blocks due to suspected fraudulent activity or unapproved international routes.
What You Should Do
- Check the Status: Avoid repeating the transfer immediately. Look at your app’s transaction history and save the transaction reference/receipt.
- Confirm with the Recipient: Ask the beneficiary or merchant to verify if their bank actually received the value.
- Contact Your Bank: If the money does not reverse automatically within 24–72 hours, lodge a formal complaint with your sending bank.
Experiencing a failed transaction where your money is still deducted can be incredibly frustrating. In Nigeria, the Central Bank of Nigeria (CBN) strictly regulates electronic transaction failures and mandates specific auto-reversal timelines ranging from instant reversals up to 72 hours depending on the payment channel.
Why Transactions Fail But Money Is Deducted
An online payment goes through a multi-step digital “handshake” involving your bank, a switching network (like NIBSS, Interswitch, or Mastercard/Visa), and the receiving party’s bank or vendor platform.
-
- The Communication Disconnect: Your bank successfully approves the deduction and pulls the money out of your account. However, during transit, a network glitch prevents the merchant’s bank or point-of-sale (PoS) terminal from acknowledging the payment.
- Safety Hold/Pending Status: Because the loop didn’t close, the transaction logs as a “failed transaction.” The money isn’t lost in thin air; it is stuck in a clearing or settlement account between the financial systems.
Official CBN Reversal Timelines in Nigeria
The Central Bank of Nigeria heavily penalizes banks for delaying reversals. If your account is debited for an incomplete transaction, the official resolution windows apply
| Transaction Type | Official CBN Reversal Timeline |
|---|---|
| “On-Us” ATM (Your bank’s card on your bank’s ATM) | Instant. If a glitch prevents this, manual reversal must happen within 24 hours. |
| “Not-On-Us” ATM (Your card used on another bank’s ATM) | Maximum 48 hours. |
| PoS & Web/Online Purchases | Concluded within 72 hours. |
| Instant Bank Transfers (NIP) | Within 24 hours of lodging a complaint (Banks face a ₦10,000 fine per day for uncompleted reversals beyond this). |
| Failed Airtime/Data Purchases | Driven by a strict framework requiring real-time auto-refunds or a maximum 24-hour resolution window. |
Step-by-Step Guide: How to Get Your Money Back
If the auto-reversal doesn’t happen within the timeframes above, follow this plan to recover your funds:
1. Gather Your Evidence
-
- Keep your debit alert SMS or take a screenshot of your digital receipt showing the session ID or reference number.
- Check your banking app to see if the fund is under “Pending/Hold” status or if it explicitly debited your total balance.
2. Log an Official Dispense Error
-
- Open your bank’s mobile app or log into their internet banking portal.
- Look for the “Log a Dispute”, “Card Services”, or “Dispense Error” form. Filling this out logs your complaint directly into the automated settlement queue.
3. Escalate to Customer Care Channels
-
- Reach out to your bank via their verified customer service channels.
- Pro Tip: Tagging your bank on official social media handles (with your transaction details but never your card PIN/CVV) often fast-tracks the internal tracking process.
4. The Last Resort: Escalate to the CBN
- If your bank fails to return your money after the mandated period, you can email the apex regulator at cpd@cbn.gov.ng (Consumer Protection Department).
- Include your bank name, account number, transaction date, unique session ID, and evidence of your unhelpful communication with the bank.
How do I prevent “payment failed” problems in the future?
-
- Avoid running heavy transactions during known peak hours (like Friday evenings or public holidays) when networks are heavily congested.
- Make sure your banking app is updated to the latest version to avoid software handshake bugs.
- Always wait a few minutes before retrying a timed-out transaction to avoid double debits.
What It Really Means When You Are Debited But The Transaction Fails
When a bank debits your account even though the transaction fails, it does not automatically mean your money is lost. What it actually means is that your transaction started successfully and your your account was charged during the process. But something interrupted completion. In simple terms, your money is in what bankers call, which is called “a temporary processing state”.
This means that the system has recognized and removed the money but the final delivery (cash or transfer) did not happen. So, the issue is usually a processing failure, not a disappearance of funds.
Common Scenarios Where This Happens
1. ATM Withdrawal Failure
This is one of the most frequent causes of this issue in African banking system, especially Nigeria. The issue starts when you request for cash withdrawal through the ATM. You insert your card, request cash and immediately you receive a debit alert without the ATM dispensing cash.
Why did this happen? The ATM may run out of cash mid-transaction, meaning the system already debited you but cannot dispense money, or there may be a network disruption between the ATM and your bank during processing or the ATM machine itself may develop a hardware fault, stopping it from completing the transaction. This means that the system has already recorded your request and processed the debit, but the machine could not fulfill the physical cash part of the transaction.
2. POS Payment Failure
This often happens in shops, agents, supermarkets, or fuel stations. The POS machine displays “Transaction Failed” after the customer must have inserted their cards to consummate the transaction, but their account is debited.
What happens at this process? There may be a delay in communication between your bank and the merchant’s bank or the POS terminal may experience network instability or the transaction may partially process before a system timeout occurs. This means that your bank has recognized and processed your payment request, but the merchant’s system did not receive confirmation, resulting in failure.
3. Mobile Transfer Failure (Mobile App & USSD)
A lot of bank customers faces this issue. This happens during bank app or USSD transfers when you try to send money meant for business purposes or your relation, but the transaction fails or remains pending, but your account is debited during this process. All these happens because interbank transfers depend on multiple systems and not just your bank, there may be delays from payment switch network or probably your banking app may experience processing errors.
What this means is that the debit occurred at your bank level, but the receiving bank did not confirm the transaction successfully.
Why Banks Debits You Even When the Transaction Doesn’t Go Through
This is the most misunderstood part of this entire issue. Here I will discuss why banks debits you, even though the transaction fails. Here are why:
1. Transactions Happen in Stages -Banking transactions are not a single instant action. They occur in phases:
- Authorization — Your bank verifies you have enough money
- Processing — The system begins transferring the funds
- Confirmation — The receiving system confirms success
Why does this matter to you as a bank customer? If the transaction fails after authorization or during processing, your account may already be debited but confirmation is never completed.
2. Network Dependencies in Africa or The Nigerian Banking System
Banking systems rely on multiple interconnected platforms which are your bank, the receiving bank, the payment switching systems and the digital networks. If any one of these systems delays, disconnects or fails to respond, it can interrupt the transaction midway.
3. System Timeouts
Every transaction has a time limit to complete. If a system does not receive confirmation within a set time, it automatically cancels the transaction. But in many cases, the debit had already happened before the timeout occurred. This results in “failed transaction or Debit alert.
4. Interbank Communication Delays
When money moves between different banks, your bank sends the instruction instantly and the receiving bank must confirm receipt. The reason why delays happen is because:
- Receiving bank systems may be slow
- Network congestion may affect communication
- Settlement processes may not be immediate.
During this period, debit happens, but confirmation is delayed or fails. Now, will you get your money back? Yes. In most cases, your money will be reversed immediately but the issue is not recovery but how long it takes.
How Long Does The Reversal Process Takes?
If the issue happened within the same bank, reversal can happen within minutes or hours. Why would this happen faster? This is because both the sender and the receiver are within one system, therefore, no external verification is required.
Also, if the transaction is interbank transfers, that is for transfers between different banks, it may take 24 to 72 hours. This will be slower because banks must
- Check records across systems
- Confirm failed delivery
- Balance accounts between institutions
Finally, for failed transactions that occurred within ATM and POS, it may take 3 to 5 working days. This is because:
- ATM transactions require machine logs to be checked
- POS transactions involve merchant banks
- Disputes may require manual verification
What You Should Do Immediately
1. Stay calm and avoid panic. Although it feels alarming, this is usually a recoverable system issue, not permanent loss. Panicking can lead to making repeated transfers and this can worsen the situation.
2. Always check your transaction status before committing another one. Please verify your bank app transaction history and SMS alerts. This is important because most times, the transaction may later go through or reversal may already have started.
3. Always allow time for auto-reversal. Many banking systems are automated, this means that failed transactions are often flagged and systems automatically trigger refunds. So wait a few minutes or hours and monitor your account.
4. Report to your bank immediately if delay persists or if money is not reversed. You can do this through customer care phone lines, bank mobile apps or try visiting a branch. Reporting your failed transaction will trigger or escalate your case into manual review and faster resolution.
5. Provide complete transaction details when reporting your failed transaction. You should try as much as you can to capture exactly amount debited, transaction date and time and transaction type (ATM, POS, transfer). Providing clear details helps bank staff to trace your transaction faster and avoids delays in investigation.
6. Try to keep evidence of the transaction. Always try to save Screenshots, transaction reference numbers and debit alerts. These are proofs that strengthens your claim and speeds up your resolution.
When Should You Take It Seriously?
Although, most failed transaction cases are resolved, still escalate if there is no refund after several working days or if the bank’s response is unclear or the transaction cannot be traced. What should you do? Push for escalation within the bank system until resolved.
How to Prevent Failed Transactions in the Future
There are various factors that cause failed transaction, and as a bank customer, you need to very sensitive to these variables to stay away from incessant debits. Below are some of the things to note.
1. Avoid Peak Transaction Periods
High traffic periods like salary days or month ends overload banking systems, and this results in slower systems and higher failure rates.
2. Use Stable and Reliable Channels
Not all channels perform equally, therefore use the banks mobile apps over instead of USSD. Some people prefer using the app than USSD channel due to issues associated with the USSD failures. It is also good to avoid poorly maintained POS terminals. This will save you some stress about transaction reversal.
3. Ensure Strong Network Connectivity
Weak internet increases transaction failures. This is because transactions rely on real-time communication. Therefore ensure you have a strong network connectivity before making any online transaction.
4. Avoid Repeated Transactions
Retrying failed transactions multiple times can multiply debits and create confusion in reversals.
5. Maintain Proper Records
Always keep transaction records because records helps to resolve issues faster if problems occur.
6. Avoid running heavy transactions during known peak hours (like Friday evenings or public holidays) when networks are heavily congested.
7. Make sure your banking app is updated to the latest version to avoid software handshake bugs.
8. Always wait a few minutes before retrying a timed-out transaction to avoid double debits.
Insider Insight (Real Banking Experience/Perspective)
From my experience over the years as a bank staff and through banking operations had so far, delays are rarely intentional. They typically happen because systems reconcile transactions in batches (as they were reported on the system), interbank disputes require verification and fraud checks may temporarily hold transactions. So what customers experience as “delay” is often system-driven processing, not manipulation. This is true because banks protects their customer’s funds.
Frequently Asked Questions (FAQ)
Why did my bank debit me without completing the transaction?
Because the debit occurred during processing, but the transaction failed before completion.
How long will it take to get my money back?
It can take from a few hours to 3–5 working days, depending on the transaction type.
Can my money be lost permanently?
Very unlikely. Most failed transactions are reversed.
Should I contact my bank immediately?
Wait briefly for auto-reversal, then report if it delays.
Who is responsible for the issue?
Usually your bank handles resolution, even if another bank is involved.
Does a failed transaction show on a bank statement?
Yes. Usually, you will see the debit entry reflecting the outflow. Once resolved, you will see a corresponding “Reversal” or “Credit” entry. In some modern fintech apps, the failed debit simply disappears from your ledger once dropped from “pending” status.
How long does a failed transaction stay pending?
Typically 24 to 72 hours. Financial systems perform end-of-day reconciliations. If the merchant’s bank doesn’t claim the funds because the transaction failed on their end, the hold is automatically released back to your available balance.
Conclusion
Being debited for a failed transaction is frustrating, but it is a very common issue in Africa/Nigeria’s banking environment. The key things to remember is that your money is usually not lost, the issue is system-related and finally, reversals are almost always processed.
What separates a calm customer from a frustrated one is that a calm customer understands the process, knows what action to take and knows when to escalate. With this knowledge, you are now in control.