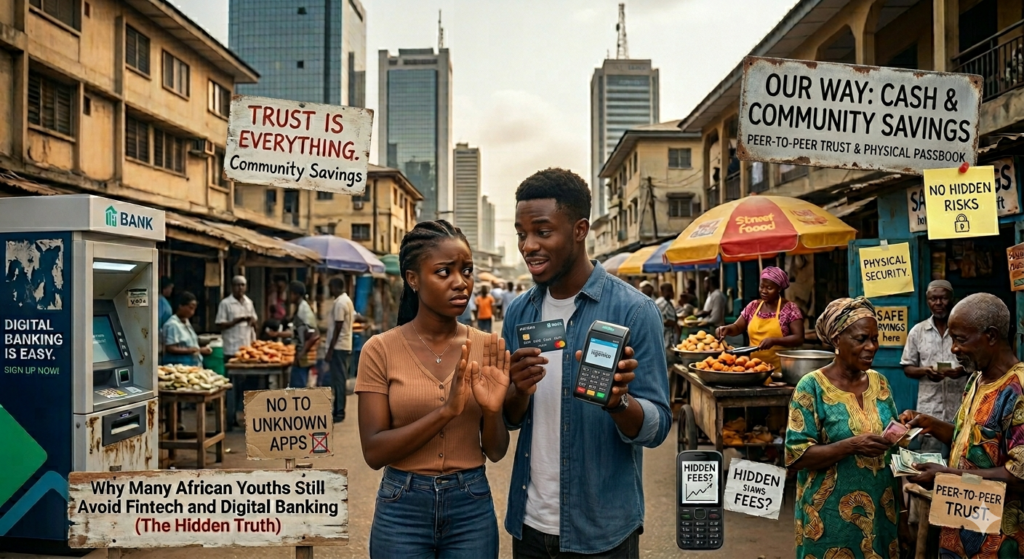
African youths avoid fintech platforms primarily due to a profound trust deficit caused by frequent system downtime, delayed transaction reversals, high internet data costs, and fear of digital fraud. Additionally, a cash-dominated informal economy and a lack of official government identity documentation lock millions of digital-only users out of the neobanking ecosystem.
- Poor Customer Support: Lack of physical branches and human help during transaction failures creates severe financial anxiety.
- High Transaction Costs: Hidden micro-fees and withdrawal levies erode tight daily budgets.
- Data and Device Taxes: Expensive mobile internet data and heavy app requirements create a continuous financial drain.
- The Cash Ecosystem: Over 90% of local retail transactions require physical cash, making app-to-cash conversions expensive.
- Strict KYC Barriers: A lack of government-issued identity documents blocks automated digital registration.
| Why Youths Use Cash | Why African Youths Avoid Fintech Apps |
|---|---|
| Instant Settlement: Free, zero-network dependency. | System Risks: High downtime and trapped funds. |
| No Hidden Fees: You spend exactly what you have. | Micro-Charges: Continuous deductions per transaction. |
| Universal Acceptance: Accepted by all informal merchants. | Conversion Friction: Agent fees required to withdraw cash. |
| Complete Privacy: Safe from digital fraud and phishing. | Security Holes: Vulnerable to social engineering scams. |
Across Africa, fintech is booming. Mobile apps, digital wallets, and online banking platforms are transforming how people save, spend, and transfer money. From Kenya’s M‑Pesa to Nigeria’s Paystack, innovation is reshaping financial services at an unprecedented pace. Yet, behind this rapid expansion lies a surprising reality: many African youths remain hesitant to fully embrace digital banking.
This reluctance is not due to ignorance. African youths are among the most digitally active populations in the world, spending hours daily on social media, streaming platforms, and e‑commerce sites. The issue is deeper, it is about trust, reliability, and lived experiences. Understanding these challenges is crucial for fintechs and banks that hope to win over the continent’s young population. So what is the real problem?.
Why African Youths Avoid Fintech: The Realities of Digital Banking
1. The Broken Promise of Customer Care
The “Trapped Money” Nightmare
Aggressive Practices and Lack of Dignity
2. The High Cost of “Free” Digital Apps
+-----------------------------------------------------------------+

|               THE HIDDEN COSTS OF GOING DIGITAL                 |
+--------------------------------+--------------------------------+

| Expensive Internet Data        | Battery and Network Lifelines  |
| 1GB of mobile data can swallow | Constant power outages and     |
| up to 8% of a youth's monthly  | network failures leave users   |
| income in many regions.        | stranded at the checkout line. |
+--------------------------------+--------------------------------+
The Smartphone and Data Charges
Network DOWNTIME and Power Outages
3. Cash Controls the Real Economy
Income Earned (Cash) ──> Deposited to App (Incurs Fees) ──> Withdrawn to Cash (Incurs Fees) = Loss of Real Value
The Reality of the Local Market
4. Evolving Fraud and the Trust Deficit
   ┌────────────────────────────────────────────────────────┐
   │             The Digital Vulnerability Loop             │
   └───────────────────────────┬────────────────────────────┘
                               │
            Low Digital Financial Literacy
                               │
                               ▼
            Targeted Phishing & Social Engineering
                               │
                               ▼
            Financial Loss Without Clear Help
                               │
                               ▼
            Complete Exit from the Tech Ecosystem
The Threat of Social Engineering
5. Paperwork Barriers and Cultural Mismatches
- The Identity Document Gap: Nearly 30% of adults in Sub-Saharan Africa do not possess a government-recognized national ID card. Without this paperwork, they instantly fail automated app verification checks.
- The Gig-Economy Hurdle: Many young Africans earn money through freelance work, social media, or informal trading. Digital apps often demand formal corporate tax certificates or traditional salary slips to clear transaction limits—documents that independent workers simply do not have.
- Ignoring Community Saving Models: Historically, our people save through community groups like Stokvels, Esusu, or Chamas. These rely on human relationships and collective trust. Most financial apps are designed for isolated, individual use, completely missing the cultural importance of communal finance.
Inside the Vault: Real Steps to Fix the Divide
- Bring Back Human Support: Give users a clear, immediate way to reach a human being when a transaction fails. If you don’t have a physical branch, build hybrid support kiosks in local markets.
- Eliminate the Micro-Fees: Stop charging users for every single balance inquiry, notification, and minor transfer. Transparent, flat pricing builds long-term loyalty.
- Build Lightweight Apps: Optimize software to run smoothly on low-end smartphones and low-bandwidth networks without draining a user’s data package.
- Integrate with the Cash Economy: Stop trying to kill cash overnight. Create tools that help users transition smoothly between physical money and digital savings without taking a bite out of their income.
Reasons Why African Youths Avoid Fintech
1. Trust Related Issues in Financial Institutions
Trust is the bedrock of finance, it is the biggest barrier and many young Africans feel it is fragile. Years of failed transactions, unauthorized debits, and stories of inefficiency have created skepticism. For example, when a transfer disappears into a “black hole” or a dispute drags on for weeks, users conclude: “My money is not fully safe.”
Even modern fintech apps, despite sleek designs and marketing campaigns, inherit this distrust. Youths often assume that if traditional banks can fail them, digital platforms might too. Without visible safeguards and quick resolutions, fintechs struggle to overcome this psychological barrier.
2. Fear of Fraud and Scams
Fraud is a growing concern. Phishing emails, fake apps, and social engineering scams target young people precisely because they are active online. In Nigeria, for instance, “Yahoo Yahoo” scams have become infamous, reinforcing the perception that digital money is risky.
Faced with these threats, many youths prefer cash or informal systems like peer‑to‑peer lending circles. These may lack efficiency but feel safer. Until fintechs demonstrate robust fraud prevention and communicate it clearly, fear will continue to slow adoption.
3. Poor Network and System Failures
A major issue in Nigeria and other African countries is network reliability which is another stumbling block to poor adoption of fintechs and digital banking by youths. Unstable internet connections, app downtime, and failed transfers (where money is debited but not received) are common frustrations. This creates what experts call the “friction loop problem”: every failed transaction erodes confidence, making users less likely to try again.
Imagine needing to pay for transport or groceries with your mobile app, only for the app to freeze or decline and you got debited. In such moments, cash feels more dependable. For fintechs, solving reliability issues is not optional, it is the difference between growth and abandonment.
4. Lack of Financial Literacy
Digital banking requires more than just downloading an app; it demands understanding. Many young people misinterpret technical errors as fraud or remain unaware of basic security practices like two‑factor authentication. This knowledge gap breeds or creates fear. A youth who loses money due to a simple mistake may avoid fintech entirely. Financial literacy campaigns delivered in simple, relatable language, are essential to bridge this gap.
5. Data Privacy Concerns
With rising awareness of data misuse, African youths are asking tough questions: Who controls my information? Can my data be sold or leaked? Without transparent answers, fintech companies risk losing credibility. Privacy policies buried in fine print do little to reassure users. Clear communication, visible consent options, and demonstrable safeguards are needed to build confidence in digital platforms.
6. App Complexity and Poor User Experience
Not all fintech apps are user-friendly. Complicated interfaces, multiple steps for simple transactions, and hidden charges frustrate young users. Youths prefer speed and simplicity. If sending money through an app requires navigating five screens or options, users will abandon the app. Successful fintechs must prioritize clean design, intuitive navigation, and transparency in fees.
7. Cultural and Behavioral Factors
Cash is still deeply rooted in African economies. Many youths grew up seeing physical money as “real” and trust face‑to‑face transactions more than digital ones.
Digital money, by contrast, feels intangible. For some, it lacks the psychological reassurance of handing over cash. Changing this mindset requires not just technology but cultural adaptation, therefore fintechs must show how digital money can be as “real” and reliable as cash.
8. Negative Word‑of‑Mouth
In Africa, experiences spread quickly. A single failed transaction can be shared on WhatsApp, discussed among friends, and amplified on social media. This creates collective fear, even among people who haven’t experienced the issues themselves. This ripple effect means fintechs must treat every user experience as critical. One unresolved complaint can damage reputation across entire communities.
What Fintechs and Banks Must Do
Winning over African youths requires more than innovation, it demands confidence‑building. Therefore, institutions must:
- Build Trust: Transparent processes, quick dispute resolution, and visible safeguards.
- Improve Reliability: Reduce downtimes, fix failed transaction issues promptly, and ensure stable connectivity.
- Simplify Apps: Clean interfaces or user friendly interface, fewer steps, and clear fee structures.
- Educate Users: Launch financial literacy and security awareness campaigns tailored to youth culture.
- Strengthen Security Communication: Not just being secure, but showing it clearly through visible features like fraud alerts and biometric authentication. I think Opay digital services does this.
Here is my thought as a Bank staff:
Fintech adoption in Africa is not just about availability, it is about confidence. The challenge is not technological but psychological. Or let me simply say that this is not just a technology problem, it is a trust and experience problem. Therefore banks and fintechs that will win in Africa are those that:
- Understand user fears
- Design for real-life challenges
- Build human-centered digital banking
Frequently Asked Questions (FAQs)
Why do some young people prefer traditional bank branches over digital apps?
Do transaction fees really stop people from using banking apps?
How does missing identity paperwork affect app adoption?
Conclusion
Fintech in Africa is growing rapidly, but adoption among youths remains cautious. The barriers are clear: trust deficits, fraud fears, unreliable systems, poor literacy, privacy concerns, complex apps, cultural habits, and negative word‑of‑mouth. To overcome these, fintechs must go beyond technology. They must build trust, ensure reliability, simplify user experiences, and educate users. Only then will African youths embrace digital banking fully. The future of fintech in Africa is bright, but only for institutions that recognize that adoption is not just about apps, it is about confidence.