Cheque Clearing Fraud in Banks: The Ultimate 2026 Guide to Methods, Prevention, and Liabilities
In today’s fast-evolving financial system, digital banking, instant transfers, and fintech platforms dominate the conversation. Yet across Nigeria and much of Africa, cheques remain a trusted tool, especially for high-value business transactions, contract payments, and corporate settlements. However, beneath this familiarity lies a critical vulnerability that many individuals and businesses underestimate: “The Clearing Cheque Fraud”.
Despite the massive rise in instant digital banking channels, traditional paper cheques remain a massive vector for financial crime. According to global data, check-based fraud accounts for roughly 30% of all fraud losses at financial institutions, making it the number one payment fraud threat facing community banks and commercial enterprises
This form of fraud continues to cost victims millions of naira yearly, not because of technological sophistication, but because of timing, trust, and misunderstanding of how cheque clearing actually works.
A common scenario plays out repeatedly:
- A cheque is deposited
- The amount appears in the account
- The customer feels secure
- Goods or services are released
Then suddenly, days later, the bank returns the cheque with alarming remarks like, “Spurious, Forged or Drawers Confirmation Requires/ Drawers Attention Required, Account Not Funded Or Refer to Drawer”. At that point, the damage is already done.
This in-depth guide covers exactly what people are searching for regarding cheque clearing fraud in banks, how it works, the specific tactics criminals deploy, who bears the liability when things go wrong, and how to stay safe.
What Is Cheque Clearing Fraud In Banks?
Cheque clearing fraud occurs when an individual uses a fake, altered, unauthorized, or unfunded cheque to deceive a victim during the clearing window, the period between deposit and final confirmation. To understand this fraud clearly, it’s important to understand the clearing process itself.
How Cheque Clearing Works in Reality
When a cheque is deposited, it does not instantly become valid cash. Instead, it goes through a structured process. The cheque is deposited into the beneficiary’s account, then the receiving bank forwards it to the paying bank. The paying bank verifies signatures, account status, and funds. Finally settlement is completed only after successful validation. This typically takes 1 to 3 working days (or longer for interbank clearing).
┌────────────────────────┐       Delayed       ┌────────────────────────┐
│ Cheque Deposited       │ ──────────────────► │ Value Appears on App   │
│ (Clearing Period Start)│   Clearing Window   │ (But is NOT Cleared)   │
└────────────────────────┘                     └───────────┬────────────┘
                                                           │
                                                           ▼
┌────────────────────────┐       Returns       ┌────────────────────────┐
│  Bank Reverses Funds   │ ◄────────────────── │ Fraudster Liquidates   │
│  (Victim Owes Money)   │    "Bad Cheque"     │ Account / Flees        │
└────────────────────────┘                     └────────────────────────┘
Where the Fraud Happens
Fraudsters exploit this delay by creating a false sense of financial security during the waiting period, knowing that:
- The cheque has not been fully validated
- The victim may see the amount appear probably in their app or ledger balance.
- Emotional pressure can override caution
In simple terms, the fraud lives inside the “waiting period.”
How Cheque Clearing Fraud Works (Step-by-Step Breakdown)
Understanding each stage of the fraud helps both customers and bank staff identify risks early.
Step 1: Issuance of a Fraudulent Cheque
The fraud begins with a cheque that is intentionally compromised. This may involve a stolen cheque leaf taken from a genuine account holder, a forged signature imitating the account owner, an altered cheque where figures or names are changed and a cheque drawn on an account with little or no funds. At this stage, the cheque may look completely legitimate, especially to an untrained eye.
Step 2: Deposit and Illusion of Funds
Once the cheque is deposited, it may reflect as “uncleared funds” and in some cases, banks may show temporary credit or available balance. This is one of the most dangerous phases because visibility is often mistaken for validity.
Many victims wrongly assume: “If I can see the money, it must be real.”
Step 3: Creation of Urgency
This is where psychology comes in. Fraudsters will quickly introduce pressure with some words like, “I need urgent delivery today”, “The cheque has already cleared” or “You can confirm from your app”, This urgency is deliberate. It is designed to prevent verification, rush decision-making and create emotional pressure. Fraud thrives where urgency cancels caution.
Step 4: Release of Value
At this step, the victim takes action because goods are released, cash is withdrawn, services are delivered and contracts are executed. This is the point of irreversible loss, because value has changed hands before actual payment is confirmed.
Step 5: Cheque Rejection (Too Late)
After verification, the paying bank rejects the cheque due to forgery, insufficient funds or account irregularities. The cheque is returned with remarks such as:
- “Spurious”
- “Forged”
- “Insufficient Funds”
The receiving bank reverses the credit, and by this time, the fraudster is gone and recovery is extremely difficult.
Real-Life Scenario (Nigeria Context)
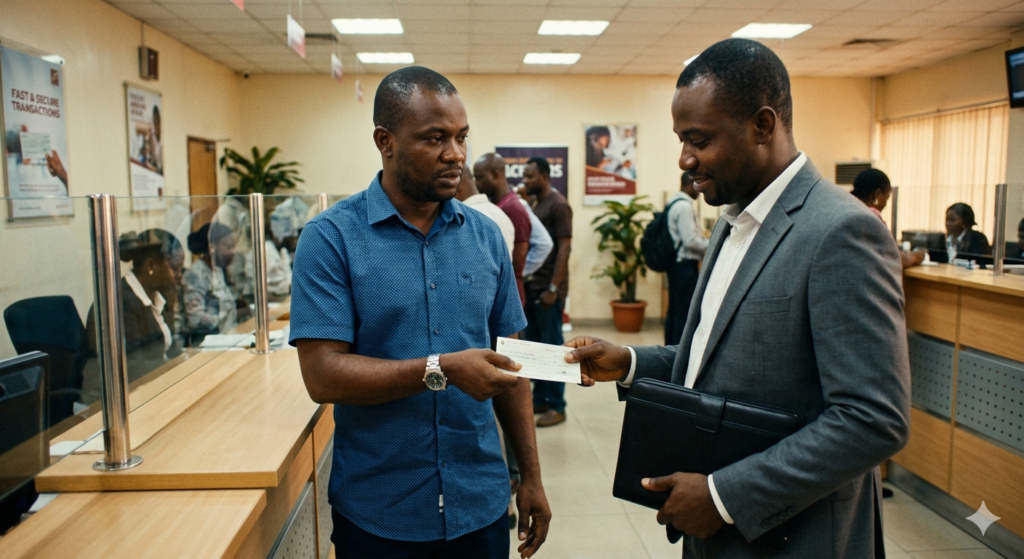
Consider this realistic case where a Lagos-based trader receives a cheque worth ₦7.5 million from a new customer. The cheque is deposited and reflects as an uncleared balance. Shortly after, the customer insists on urgent delivery, claiming the cheque is valid. Trusting the transaction, and seeing the amount reflected on his mobile app, the trader releases the goods. Two days later, the cheque is returned with reason “Spurious/Forged”. At that moment:
- The goods are gone
- The customer is unreachable
- The bank reverses the funds
Total loss stood at a whooping ₦7.5 million. This is not rare, it is a recurring pattern across commercial hubs.
Common Types of Cheque Fraud (From A Bank Staff)
Understanding variations or the common cheque frauds helps improves detection. Below are the the different ways through which cheque fraud is committed.
1. Forged Cheques
These involve fake signatures or manipulated account details. Fraudsters often study signature patterns before attempting this. This happens when a fraudster imitates the account holder’s signature or details to make the cheque look legitimate.
To the bank or seller, it may appear genuine at first glance, but the signature verification will eventually fail.
2. Altered Cheques
Here, a genuine cheque is modified, typically the amount or payee name is changed to increase value or redirect funds. Most times the date will be modified if the fraudster notice that the date is stale.
Here, a real cheque is tampered with, usually by changing the amount or the beneficiary name. For example, a ₦50,000 cheque can be altered to ₦500,000 without the issuer’s knowledge.
3. Stolen Cheques
Cheque books stolen from customers are used before the account holder becomes aware. Fraudsters steal cheque leaves from individuals or businesses and use them before the owner notices. Since the cheque itself is real, it becomes harder to detect immediately.
4. Cheque Kiting
A more sophisticated method involving multiple accounts, where fake balances are created using circulating cheques. Or simply say it’s a more advanced fraud where someone uses multiple bank accounts to create fake balances, moving cheques between them. It gives the illusion that money exists when it actually doesn’t.
5. Counterfeit /Cloned Cheques
This happens when an entirely fake instruments is printed to resemble legitimate bank cheques. These are completely fake cheques printed to look like genuine bank instruments. They may carry logos and designs that resemble real banks but have no backing account.
Utilizing sophisticated commercial printers, scanners, and high-quality paper stock, fraudsters fabricate entirely fake cheques containing real bank routing numbers. This often includes duplicating high-value instruments; to understand why these specific assets are targeted, see this deep dive on Manager’s Cheque vs Normal Cheque: Why Businesses Prefer It And How It Works.
Why Cheque Clearing Fraud Still Exists
Despite banking controls, this fraud persists due to a combination of human and systemic factors. Some of the factors include:
1. Human Trust
People tend to trust visible balances and verbal assurances without full verification. People often trust what they see in their account and act quickly under pressure. Fraudsters take advantage of this emotional response.
2. Lack of Awareness
Many customers do not understand the difference between available balance and cleared funds or people don’t fully understand what “uncleared funds” means. So they assume money is available when it is not yet confirmed.
3. Operational Lapses/Gaps In Banks
In some cases, staff may fail to properly caution customers or flag suspicious transactions. Sometimes, bank processes or staff actions may not fully prevent risky transactions. Small lapses can create opportunities for fraud to succeed.
4. Weak Verification Process
Businesses often skip basic checks when dealing with new or unknown customers. Customers and businesses often skip proper checks, especially when transactions feel urgent. This shortcut is what fraudsters rely on.
5. Delays in Clearing Systems
The time it takes to confirm a cheque gives fraudsters a window to act. The longer the delay, the higher the risk. Therefore, the longer the clearing window, the more opportunity for fraud. Fraud exists where knowledge is low and speed is high.
How Bank Customers can Prevent Cheque Clearing Fraud
1. Never Act on Uncleared Funds
If the cheque is not fully cleared, treat it as non-existent money and do not release your goods. Seeing the balance does not mean it is safe.
2. Verify with the Paying Bank
For high-value cheques, always confirm authenticity, check funding account and validate cheque issuance. This step alone can prevent most losses and ensures the cheque is real and properly funded.
3. Resist Urgency
A legitimate customer will always allow time for proper verification. They will not pressure you to release goods when cheque has not cleared. Pressure is often a sign of deception. If someone is rushing you, be cautious, genuine transactions allow time for proper checks.
4. Use Safer Payment Methods
Always encourage your prospective customers or clients to use bank transfers (this can be done inside the banking premises or via mobile app), verified electronic payments channels or the escrow arrangements. So use transfers or electronic payments instead of cheques where possible. These methods are faster and more reliable.
5. Apply Practical KYC
Before large transactions, confirm identity of the customer, verify their business legitimacy and avoid unknown walk-in transactions. Always verify who you are dealing with before accepting large payments. Fraud is more common with unknown or new customers.
How Banks Can Prevent Cheque Fraud
1. Advanced Verification Systems
Banks can use better systems to check signatures and detect unusual transactions. Technology helps identify fraud earlier. So banks should adopt:
- Signature recognition technology
- AI-based fraud detection
- Behavioral anomaly monitoring
2. Improve Customer Awareness
Educating customers reduces mistakes and risky decisions. Awareness is one of the strongest defenses. Banks must actively inform customers about risks of uncleared funds, the meaning of cheque status and safer alternatives.
3. Restrict Instant Value/Limit Automatic Credit
Banks should avoid allowing customers to access large cheque funds immediately. This reduces the chance of premature withdrawals. They should also avoid immediate credit on large interbank cheques, especially for:
- New customers
- High-risk transactions
4. Enhance Interbank Communication/Improve Clearing Efficiency
Faster interbank communication can reduce fraud opportunity windows or say faster communication between banks helps verify cheques quicker. This shortens the fraud window.
5. Train Frontline Staff
Well-trained staff can spot suspicious transactions early. Frontline employees are key to prevention.
Staff must be equipped to:
- Identify suspicious patterns
- Engage customers proactively
- Prevent risky withdrawals
The 7 Most Common Types of Cheque Fraud
- Check Washing: Criminals steal legitimate paper cheques from postal mail and use basic chemical solutions (like acetone or bleach) to erase the payee’s name and the dollar amount while leaving the original signature intact. They then rewrite the cheque to a new beneficiary for thousands more.
- Counterfeit Cheques: Utilizing sophisticated commercial printers, scanners, and high-quality paper stock, fraudsters fabricate entirely fake cheques containing real bank routing numbers and stolen active account numbers.
- Double Presentment (Duplication): With the birth of Remote Deposit Capture (RDC) apps, a fraudster can take a picture of a valid cheque to deposit it via their mobile banking app, then immediately walk into a physical retail branch or check-cashing store to cash the same physical paper leaf a second time.
- Altered Amounts & Erasures: Manipulating the written numbers or words directly on the face of the leaf (e.g., changing $100 to $10,000) using specialized pens or ink alterations.
- Forged Signatures: Acquiring stolen blank cheque books through house break-ins or internal corporate leaks and forging the authorized account holder’s signature.
- Check Kiting: An illicit scheme where an individual takes advantage of the float time in a multi-bank network by writing cheques back and forth between two or more un-funded bank accounts they control, artificially inflating their balances to access short-term, interest-free “loans”.
- Paper Hanging: Intentionally writing cheques on closed accounts or accounts that the criminal knows have zero funds available.
Who Takes the Loss? Legal Liabilities Explained
- Visible Fault Rule: If a cheque contains visible alterations, erasures, or discrepancies under Ultra-Violet (UV) light, the presenting bank (the bank that accepted the deposit) is typically held fully liable for failing to catch the flaw at the front door.
- Irregularity Sharing: If a cheque is processed despite containing structural errors (like being stale-dated, post-dated, or having mismatched figures and words), both the presenting bank and the paying bank may be forced to split the loss 50:50.
- Customer Carelessness: If a business owner willingly hands over physical goods before a cheque fully clears the mandatory processing cycle, the customer absorbs the direct financial loss. The bank is not required to reimburse funds spent or credited provisionally from an unfunded transaction.
Key Red Flags You Should Never Ignore
Be cautious when you notice:
- A new customer presenting a large cheque – Be careful when someone you don’t know brings a high-value cheque. This is a common fraud pattern.
- Urgent delivery or withdrawal requests – Fraudsters usually push for speed. Urgency often hides verification gaps.
- Interbank cheques for high values – These take longer to clear, increasing risk. Therefore more time, more opportunity for fraud.
- Third-party payment transactions – Payments involving multiple people can be suspicious. It makes tracking and verification harder.
- Inconsistent or unverifiable identity – If the person’s details don’t match or seem unclear, be cautious. This is often a warning sign. If a transaction feels rushed, pause and verify.
Practical Check Fraud Prevention Strategies
- Cross Your Cheques: Always draw two parallel lines on the top left corner of a paper leaf and write “Account Payee Only”. This legally ensures that the funds cannot be casually cashed over the counter and must only be routed into a verified bank account.
- Utilize Positive Pay Services: Businesses should enroll in their commercial bank’s Positive Pay network. Under this system, you send an electronic list of all issued cheques (cheque numbers, amounts, and payee names) to the bank ahead of time. If someone tries to clear a cheque that does not exactly match your digital list, the system automatically blocks the withdrawal.
- Avoid Mail Processing for Paper Assets: Given the high risk of mail-theft check washing, use online bill pay or direct electronic methods (such as wires or instant bank transfers) for high-value financial transactions.
- Never Sign Blank Leaves: Never pre-sign a blank cheque leaf for “convenience” or “verification” purposes, as this completely strips away your baseline institutional fraud protection.
- Protect the MICR Code: When disposing of a canceled or spoiled cheque, completely shred or cross out the magnetic numbers at the bottom (the MICR code) so it cannot be replicated or used for digital scanning fraud.
Frequently Asked Questions (FAQ)
1. What is cheque clearing fraud in banks?
2. How long does a cheque take to fully clear in a bank?
3. Can a bank reverse a cleared cheque if it turns out to be fraudulent?
4. What is check washing fraud?
5. Who is held legally liable for losses from a fake cheque?
6. What does crossing a cheque mean, and how does it prevent fraud?
7. How does a bank’s Positive Pay system protect businesses?
8. What is the difference between a ledger balance and an available balance?
9. Can a fraudster use my bank routing and account numbers from a cheque?
10. How can I verify if a cheque is authentic before accepting it?
Conclusion
Cheque clearing fraud is not just a technical issue, it is a behavioral and knowledge gap problem. The biggest mistake people make is believing: “Once the cheque is deposited, the money is safe” this is completely false. Until the cheque is fully cleared and confirmed, the funds are not guaranteed.
Therefore, before you accept another bank cheque from someone especially from entirely a new person, try and take note of the following points I will drop below.
- Cheque fraud exploits the delay in clearing systems
- Fraudsters rely heavily on urgency and psychological pressure
- Most losses occur when value is released too early
- Prevention depends on discipline, verification, and awareness
- Banks and customers both share responsibility
Finally, as per my experience in the banking sector, I will share this that as financial systems continue to modernize, one reality remains clear: “Legacy payment systems still carry modern risks” Let’s try to understand that technology alone cannot stop fraud. The real protection lies in, staff knowledge, verification discipline and situational awareness, because in banking, especially in cheque transactions, “What you see is not always what you have”.